Category: News

  • Sebi’s CAS Changes Shift Expiry-Day Trading Dynamics

    Sebi’s CAS Changes Shift Expiry-Day Trading Dynamics

    The Securities and Exchange Board of India (SEBI) has announced significant changes to the Closing Auction Session (CAS) that are set to reshape expiry-day trading and settlement processes for index and stock derivatives. These proposals, unveiled on September 12, 2026, aim to enhance market efficiency and liquidity, reflecting insights gained since the introduction of CAS in August 2026.

    Among the key changes are new settlement timelines and methods for determining expiry-day prices. Traders will need to adjust their strategies to navigate these modifications effectively. The proposed adjustments include two options for calculating settlement prices and a reduction in the transition period between continuous trading sessions and CAS.

    New Settlement Price Calculation Methods

    SEBI has put forth two primary options for determining the settlement price of derivatives on expiry days:

    • Blended VWAP (Volume Weighted Average Price): This method combines trades from the last 30 minutes of the continuous trading session (CTS) with those from the subsequent 10-minute CAS. By blending contributions from both periods based on actual traded values, this approach aims to provide a more accurate market price.
    • CTS VWAP: This option calculates the settlement price solely from trades executed in the last 30 minutes of the CTS, excluding CAS trades. This method maintains continuity with the pre-CAS framework, allowing traders to adjust their strategies accordingly.

    SEBI plans to transition to the Blended VWAP method after assessing the effectiveness of CAS, particularly concerning liquidity and participant familiarity.

    Streamlined Trading Timelines

    In addition to the new price calculation methods, SEBI has proposed reducing the transition period between CTS and CAS to one minute, down from five minutes. This change is designed to streamline trading and enhance auction efficiency. Furthermore, the post-CAS trading window for derivatives will be shortened to five minutes from ten minutes, necessitating quicker execution of trading strategies.

    These adjustments will require traders to enhance their decision-making and execution speed to maintain profitability. According to a report by The Economic Times, these changes are expected to significantly alter the trading landscape, compelling traders to adapt swiftly.

    Elimination of Indicative Index Value (IIV)

    Another notable change is the proposed elimination of the dissemination of the Indicative Index Value (IIV) during CAS. This decision could lead to confusion among traders, as the absence of this information may hinder their ability to gauge market sentiment and adjust their positions effectively. The lack of IIV could create an information gap, complicating informed decision-making, as highlighted in a report by CNBC TV18.

    Potential Impact on Market Liquidity

    The proposed changes could significantly influence liquidity in the derivatives market. By altering price discovery and settlement mechanisms, SEBI aims to enhance market efficiency. However, these changes may also introduce uncertainty as traders adapt to the new methods and timelines.

    Analysis from Career Ahead suggests that adopting the Blended VWAP method could improve liquidity if market participants embrace the new auction framework. Conversely, if traders struggle to adapt, trading volumes may temporarily decline as they recalibrate their strategies. The success of these changes will largely depend on how quickly traders can learn and integrate the new processes into their routines.
    Sebi's CAS Changes Shift Expiry-Day Trading Dynamics

    Additionally, the discontinuation of IIV dissemination during CAS could further complicate liquidity dynamics. Traders may find it challenging to assess market sentiment without this data, potentially leading to reduced trading activity during the auction. Market participants will need to monitor how these changes affect liquidity and trading volumes in the coming months.

    Preparing for a New Trading Environment

    As the market adjusts to these regulatory changes, traders should prepare for potential volatility and shifts in liquidity. The effectiveness of these changes will ultimately depend on how well the market adapts to the new regulatory environment. This adaptation could reshape trading strategies for the foreseeable future.

    Overall, SEBI’s proposed CAS changes represent a significant shift in the regulatory landscape for expiry-day trading in India. Traders and firms must stay informed and proactive as they navigate these evolving requirements. The implications of these changes are profound, particularly for traders in equity markets and financial analysts in investment firms. As the market adapts, traders should be ready for potential volatility and liquidity shifts, recalibrating their strategies accordingly.
    Sebi's CAS Changes Shift Expiry-Day Trading Dynamics

    Frequently Asked Questions

    What are the new settlement timelines for expiry-day trades?

    The new settlement timelines proposed by SEBI include a one-minute transition period between continuous trading and the Closing Auction Session (CAS). The post-CAS trading window for derivatives will also be shortened to five minutes.

    How will these changes affect liquidity in the derivatives market?

    These changes could impact liquidity by altering price discovery mechanisms, potentially leading to fluctuations in trading volumes as traders adjust to the new methodologies and timelines.

    What should traders do to adapt to the new CAS regulations?

    Traders should familiarize themselves with the new settlement methodologies, invest in training, and ensure their trading systems can handle the changes in timelines and compliance requirements.
  • Nifty Breaks Crucial Support; 5 Stocks to Watch

    Nifty Breaks Crucial Support; 5 Stocks to Watch

    India’s benchmark index, Nifty 50, has recently fallen below key support levels, closing at around 23,400 after a turbulent trading session. This decline is significant for investors, indicating a broader trend of market volatility driven by rising oil prices and geopolitical tensions. Analysts, including Sudeep Shah from SBI Securities, have shared their views on this downturn and provided stock recommendations for investors navigating this uncertain landscape.

    The Nifty 50 index has faced ongoing pressure, dropping nearly 2% over the past week, marking the fifth consecutive week of losses. The index has fallen from a peak of 24,774 in early August, a decline of over 1,500 points. Recent trading patterns suggest a bearish sentiment among investors, worsened by external factors like rising tensions between the US and Iran and increasing bond yields.

    Understanding Nifty’s Support Levels

    Technical analysis shows that Nifty’s recent performance marks a critical point for investors. The index has broken important moving averages, leading to a bearish outlook. The 23,100 to 23,000 range is identified as a vital support zone for Nifty. A decisive break below this level could lead to further declines, possibly reaching around 22,800 and 22,500.

    The market’s reaction to external pressures has been swift. As geopolitical tensions rise, especially in the Middle East, and oil prices fluctuate, investor confidence has weakened. The recent spike in the US 10-year bond yield to 4.97% has added to the uncertainty, prompting many to reassess their positions. The India VIX has risen, reflecting increased volatility in the market.

    Stock Recommendations Amid Market Fluctuations

    In light of these trends, Sudeep Shah has identified specific stocks that may offer short-term gains despite the broader market volatility. His insights stress the importance of focusing on stocks with strong fundamentals and favorable technical setups. The recommended stocks include:

    • LIC Housing Finance: With strong fundamentals, it is expected to benefit from ongoing demand in the housing sector.
    • Emcure Pharmaceuticals: This company has a robust pipeline and market presence, poised for growth as healthcare needs rise.
    • Five-Star Business Finance: This stock has shown resilience in the financial sector, making it a solid pick for investors seeking stability.
    • VA Tech Wabag: A player in the water treatment sector, gaining attention due to increasing infrastructure investments.
    • PNB Housing Finance: Its focus on affordable housing aligns with current market trends, making it a compelling choice for growth-oriented investors.

    As the market navigates this turbulent phase, these stock picks could help buffer against broader market declines. Investors are encouraged to conduct their due diligence and consider these recommendations within their overall investment strategy.

    Adapting to Market Volatility

    The implications of Nifty’s decline extend beyond immediate stock selections. For equity investors and financial analysts, this situation highlights the need for adaptability in investment strategies. Staying aware of market trends and technical indicators is crucial for informed decisions during volatility.

    Investors should consider how geopolitical developments and economic indicators may affect their portfolios. The current environment requires a balanced approach, where risk management is key. With the potential for further declines, evaluating exposure to high-risk assets and diversifying holdings is essential.

    The rising India VIX indicates that market sentiment remains fragile. Investors may want to adopt a more defensive stance, focusing on sectors less sensitive to economic fluctuations, such as consumer goods and utilities, which tend to perform better during downturns.

    Nifty Hits Key Support: Stock Strategies Unveiled

    Monitoring Market Developments

    The relationship between support levels and stock performance will be critical to watch in the upcoming week. The ability to respond quickly to changing conditions will be essential for seizing opportunities in this uncertain environment. The next few trading sessions will be crucial for Nifty and its constituents, as investors prepare for potential volatility.

    In summary, the current market landscape presents both challenges and opportunities. By focusing on strong fundamentals and maintaining a cautious approach, investors can navigate this period of uncertainty effectively.

    Nifty Hits Key Support: Stock Strategies Unveiled

    Frequently Asked Questions

    What are the implications of Nifty slipping below support for equity investors?

    Nifty’s decline below crucial support levels raises concerns about market volatility, impacting investor sentiment. Equity investors may need to reassess their strategies and consider defensive positions in their portfolios.

    How should financial analysts adjust their strategies in response to market volatility?

    Financial analysts should focus on technical indicators and market trends to refine their strategies. This includes monitoring key support levels and identifying resilient stocks that can withstand market fluctuations.

    What stocks did Sudeep Shah recommend for next week and why?

    Sudeep Shah recommended LIC Housing Finance, Emcure Pharmaceuticals, Five-Star Business Finance, VA Tech Wabag, and PNB Housing Finance due to their strong fundamentals and favorable technical setups, making them attractive for short-term investment.

    Sources: Our Money Now, Global Finserve, Economic Times.

  • Spain’s Economic Growth Leads to Credit Rating Upgrade

    Spain’s Economic Growth Leads to Credit Rating Upgrade

    Spain’s credit rating was recently upgraded by Scope Ratings. This reflects a positive development in Spain’s economic situation. The upgrade, announced on September 11, 2026, has important implications for the European financial landscape, particularly affecting bond markets and foreign direct investment.

    The upgrade comes amid reports of improvements in Spain’s economic performance, including a decrease in unemployment and increases in GDP growth rates. These changes indicate a shift towards greater economic stability, which may make Spain more attractive to investors. As a Eurozone member, Spain’s financial health is vital for its economy and the broader European market.

    Impact on Bond Markets and Investment Strategies

    The upgrade in Spain’s credit rating is expected to have implications for bond markets. Higher credit ratings can lead to lower yields on bonds, as investors often seek the safety of higher-rated securities. Analysts suggest that this could increase demand for Spanish government bonds, potentially driving yields down and making these investments more appealing.

    Additionally, it is anticipated that the favorable credit rating may influence spreads between Spanish bonds and other Eurozone securities, indicating growing confidence in Spain’s fiscal management. Financial analysts in Europe should monitor these developments closely, as changes in bond yields can influence investment strategies, particularly for those managing fixed-income portfolios.

    A lower yield environment may prompt investors to seek higher returns in equities or other asset classes, reshaping investment strategies to adapt to new market dynamics. Analysts note that improved credit ratings can attract foreign capital, which may further stabilize the bond market and enhance liquidity.

    Moreover, as Spain’s credit rating improves, it may create a ripple effect across Southern Europe, leading investors to reassess the risks associated with other countries in the region. This could result in increased capital flows into neighboring economies, signaling a broader recovery in the Eurozone. Investment banking professionals should consider these trends when evaluating their market positions and strategies.

    Research indicates that investment banking professionals should prepare for increased activity in the Spanish market. With a better credit rating, companies may find it easier to issue new bonds or secure financing, creating opportunities for investment banks to engage in underwriting and advisory roles. The landscape could become more competitive as firms vie for these lucrative opportunities.

    Increased Foreign Direct Investment Potential

    Spain’s credit rating upgrade is also expected to attract more foreign direct investment (FDI). Companies looking to expand in Europe may view Spain as a more viable option due to its improved economic outlook. Analysts suggest that investors prefer markets with stable economic conditions, positioning Spain favorably in this regard.

    There are expectations that FDI inflows into Spain will rise, particularly in sectors such as technology, renewable energy, and infrastructure. These sectors are critical for sustainable growth. FDI is vital for economic growth, as it brings capital, creates jobs, and fosters innovation. As foreign companies consider investing in Spain, significant capital inflows may occur in these areas.

    This trend is particularly relevant for economic policy advisors, who must understand the implications of increased investment on local economies. It is emphasized that such investments can enhance productivity and competitiveness, contributing to a more resilient economic framework.

    Spain Wins Credit Rating Upgrade at Scope on Strong Economy

    For economic policy advisors, the challenge will be to manage the influx of foreign capital effectively. Policies that facilitate investment while protecting local interests will be crucial. This may involve revising regulations or providing incentives for foreign companies to invest in key sectors. As Spain becomes a more attractive destination for FDI, investment professionals should remain alert to emerging opportunities. Identifying sectors poised for growth and understanding the competitive landscape will be essential for capitalizing on this trend.

    The potential for increased investment could reshape the Spanish economy in the coming years, leading to a more dynamic and resilient market. As Spain continues to recover, the question remains: will this upgrade lead to sustained growth and stability in the region? Or will external factors disrupt this promising trajectory? The coming months will be crucial for understanding the long-term implications of Spain’s credit rating upgrade.

    The economic recovery in Spain, as indicated by its credit rating upgrade, is a positive development for the entire Eurozone. It signals a potential shift in investor sentiment and renewed interest in Southern European markets. As this trend unfolds, finance and investment professionals should remain agile, adapting their strategies to capitalize on emerging opportunities. The implications of Spain’s improved credit rating extend beyond its borders, potentially influencing investment patterns across the Eurozone and enhancing the overall economic landscape.

    Frequently Asked Questions

    What does Spain’s credit rating upgrade mean for European bond markets?

    Spain’s credit rating upgrade is expected to lower yields on Spanish government bonds, increasing their attractiveness to investors. It could shift capital flows within the European bond markets as investors seek safer assets.

    How should investment banking professionals adjust their strategies following Spain’s credit rating change?

    Investment banking professionals should focus on opportunities arising from Spain’s improved credit rating, particularly in underwriting and advisory roles. Increased activity in the Spanish market may create competitive advantages for firms that adapt quickly.

    Spain Wins Credit Rating Upgrade at Scope on Strong Economy

    What are the implications of Spain’s improved credit rating for economic policy advisors?

    Economic policy advisors must consider the potential influx of foreign direct investment and its impact on local economies. They should develop strategies to manage this growth while ensuring it aligns with long-term economic goals.

  • NSE IPO Opens Soon; Price Band 1,700-1,785

    NSE IPO Opens Soon; Price Band 1,700-1,785

    Mumbai, India — The National Stock Exchange of India (NSE) will open its initial public offering (IPO) for public subscription on September 17, 2026. The price band is set between ₹1,700 and ₹1,785 per share. If the upper end is reached, the NSE aims to raise ₹22,561.5 crore, leading to a valuation of ₹4.42 lakh crore. This IPO is significant as it is an offer for sale (OFS) of up to 126.4 million equity shares by ten existing shareholders. Notable shareholders include the State Bank of India (SBI) and the Canada Pension Plan Investment Board (CPPIB).

    This IPO is a major event in the Indian financial landscape. It is expected to be the largest in India, surpassing Hyundai Motor India’s ₹27,870-crore issue from October 2024. The anchor book for institutional investors will open on September 16, setting the stage for this public offering. The NSE’s strong financial performance, with a consolidated profit after tax of ₹3,120 crore for the June quarter, adds to the excitement. According to the Economic Times, the IPO is expected to attract significant interest from both domestic and international investors. This reflects growing confidence in India’s capital markets.

    Impact on Equity Market Valuations

    The upcoming NSE IPO will likely influence equity market valuations. As India’s largest stock exchange, the NSE’s public listing should attract considerable investor interest. This could lead to increased trading volumes and market activity. Career Ahead’s analysis suggests that a successful NSE IPO could prompt a revaluation of other listed entities, especially in the financial services sector. The IPO’s pricing will be a critical benchmark, as noted by the Economic Times. It will influence how other companies approach their public offerings.

    Investment banking professionals should recognize that the IPO will set a benchmark for future public offerings in India. The price band for the NSE IPO will guide other companies considering going public. This could create a more competitive environment for upcoming IPOs, as companies will need to adjust their pricing strategies. Additionally, the NSE’s performance may impact the pricing strategies of companies in the pipeline, as they might want to capitalize on the momentum from this landmark IPO.

    Moreover, equity research analysts will closely monitor the NSE IPO’s performance. A strong market reception could boost confidence in the Indian equity market. This would attract both domestic and international investors. On the other hand, a weak response may lead to skepticism about future listings, affecting overall market sentiment. Analysts from various firms will likely revise their forecasts based on the IPO’s outcome. This could have ripple effects across sectors. As the IPO approaches, analysts will need to adjust their forecasts to account for potential shifts in market dynamics. This includes reassessing sectoral valuations and considering how the influx of capital from the NSE IPO may impact liquidity and investment flows.

    Opportunities for Investment Banking Roles in IPOs

    The NSE IPO creates new opportunities for investment banking professionals, especially those managing public offerings. A consortium of 20 investment banks, including Kotak Mahindra Capital Company and Morgan Stanley India, is involved. The presence of such prestigious institutions highlights the competitive nature of the IPO market. The Finance Feeds report emphasizes that executing this IPO will require expertise in underwriting and regulatory compliance. The stakes are high due to the expected capital inflow.

    As the IPO process unfolds, there will be a growing demand for skills in underwriting, regulatory compliance, and market analysis. Investment banking professionals must use their financial modeling and valuation skills to position the IPO effectively. This includes creating compelling narratives to attract potential investors. Additionally, the NSE IPO highlights the importance of relationship management in investment banking. Building and maintaining relationships with institutional investors will be crucial as the IPO progresses. Professionals must effectively communicate the NSE’s value and address any concerns from potential investors.

    Furthermore, the IPO is likely to create a ripple effect, leading to more IPOs as companies seek to benefit from increased market activity. Investment banking professionals should prepare for new mandates as companies follow the NSE’s lead. The visibility of the NSE IPO may encourage other firms to speed up their IPO plans, increasing overall activity in the capital markets. This could result in a more vibrant IPO landscape in India, with investment banks playing a key role in facilitating these transactions.

    NSE IPO Opens Soon; Price Band 1,700-1,785

    The NSE IPO’s structure as an offer for sale (OFS) presents unique dynamics for existing shareholders and potential investors. Significant entities like SBI and CPPIB will divest portions of their holdings. Career Ahead analysis shows that this OFS structure may shape investor perceptions of the NSE’s long-term value. Existing shareholders must carefully consider their positions as the IPO approaches. Their decision to sell shares reflects strategic needs, including liquidity and market conditions. For potential investors, understanding existing shareholders’ motivations can provide insights into the NSE’s future prospects.

    Moreover, the involvement of large institutional investors in the OFS highlights institutional confidence in the NSE. Their participation can signal to retail investors that the exchange is a solid investment, potentially driving demand for shares during the IPO. Analysts must assess how this dynamic affects overall market sentiment. As the IPO date nears, the relationship between existing shareholders and new investors will be critical. Equity analysts should monitor trading volumes and price movements closely, as these factors will indicate market sentiment and investor confidence in the NSE’s future performance.

    This upcoming IPO represents a financial milestone for the NSE and a pivotal moment for investment banking and equity research professionals. Insights from analyzing the NSE IPO can help shape strategies for future offerings and investment decisions. As the IPO unfolds, it will be vital to observe how market participants react to the listing and its implications for the broader financial landscape in India. The success or failure of the NSE IPO could influence future capital market activities, making it a crucial event for investment banking and equity research analysts to watch closely.

    Frequently Asked Questions

    What should investment banking professionals know about the NSE IPO?

    Investment banking professionals should focus on the competitive landscape created by the NSE IPO. With 20 investment banks managing the offering, skills in underwriting and market analysis will be essential for success.

    How does the NSE IPO affect equity research analysis?

    The NSE IPO will provide a benchmark for equity research analysts. It will influence their valuation models and forecasts for future IPOs in the Indian market. Analysts should closely monitor the market’s reception to the IPO.

    NSE IPO Opens Soon; Price Band 1,700-1,785

    What strategies should equity analysts consider in light of the NSE IPO?

    Equity analysts should reassess sectoral valuations in response to the NSE IPO. They should also consider how the influx of capital may impact liquidity and investment flows in the broader market.

  • US Core CPI Tops Forecasts, Bolstering Case for Rate Hike

    US Core CPI Tops Forecasts, Bolstering Case for Rate Hike

    The US Core Consumer Price Index (CPI) has recently exceeded forecasts. This suggests a strong chance of interest rate hikes by the Federal Reserve. Reported on September 11, 2026, this development highlights ongoing inflationary pressures in the economy. Analysts must now reassess their financial models and strategies based on this new inflation data.

    The Core CPI, which excludes volatile items like food and energy, rose by 0.4% in August. This increase surpassed expectations of a 0.3% rise. It puts more pressure on the Federal Reserve to tighten monetary policy sooner. With inflation above the Fed’s target, the implications for financial markets and economic forecasting are significant.

    Implications of Rising Core CPI for Interest Rates

    The rise in Core CPI is a key indicator for interest rate predictions. Career Ahead’s analysis shows that when inflation exceeds expectations, the Federal Reserve is likely to raise rates to stabilize prices. Historically, rising CPI has led to higher borrowing costs, which can slow economic growth. The Fed’s dual mandate of promoting maximum employment and stable prices complicates their decisions. If inflation keeps rising, the Fed may focus on controlling it over fostering job growth. This could lead to a more aggressive monetary policy than expected.

    Financial analysts must now consider these potential rate hikes when making forecasts. According to data from the Financial Post, the market is already pricing in at least two rate increases by the end of 2026. This shift requires a reevaluation of investment strategies, especially in fixed-income markets, where rising rates can decrease bond prices. As noted by Reuters, recent inflation readings strengthen the case for higher rates, suggesting the Fed may act sooner to curb inflation.

    Analysts should also monitor the Fed’s communications closely. The language in policy statements often hints at future actions by the central bank. As the Fed prepares to meet in the coming months, any hints at tightening could influence market expectations and investment decisions. The potential for rate hikes is not just a domestic issue; it also impacts global markets, especially in emerging economies sensitive to US monetary policy changes.

    Given these developments, analysts are urged to stay alert and responsive to economic indicators. The relationship between inflation, interest rates, and market behavior requires a nuanced understanding. Proactive adjustments in forecasting models are essential. The Federal Reserve’s decisions in the coming months will be crucial, shaping the economic landscape for years ahead.

    Adjustments in Financial Models Due to Inflation Changes

    With the recent CPI surge, financial analysts must adjust their economic models. Career Ahead research indicates that analysts should include a higher inflation rate in their models for accurate forecasting. This adjustment is vital, especially for sectors sensitive to interest rate changes, like real estate and consumer discretionary. Analysts should also revise their growth assumptions. Higher interest rates often lead to reduced consumer spending and investment, slowing growth in various sectors. According to macrostream.ai, businesses may face higher capital costs, prompting them to rethink expansion plans and hiring strategies.

    Moreover, anticipated rate hikes could shift consumer behavior. As borrowing costs rise, consumers may delay major purchases, affecting sectors like automotive and housing. Analysts must factor in these behavioral changes to better predict market movements. The Australian Financial Review notes that sectors such as energy and materials may see increased demand as inflation rises, suggesting a potential shift in investment focus.

    Investment portfolios will also need reevaluation. As interest rates rise, fixed-income securities may become less attractive compared to equities, leading to asset reallocations. Financial analysts should prepare for potential market volatility as these adjustments occur. Recent CPI data has already sparked discussions among investors about strategies to mitigate risks from rising rates. As noted by Bloomberg, the market’s response to inflation data will be crucial in determining interest rates and overall economic health.

    US Core CPI Tops Forecasts, Bolstering Case for Rate Hike

    In summary, the rise in Core CPI presents a complex landscape for financial analysts. The interplay between inflation, interest rates, and market behavior requires a nuanced understanding. Proactive adjustments in forecasting models are essential. The decisions made now could shape the economic landscape for years, making it vital for analysts to stay ahead.

    As the likelihood of interest rate hikes increases, investment strategies must adapt. Career Ahead’s analysis identifies sectors likely impacted, including utilities, real estate, and consumer staples. These sectors typically perform well in low-interest-rate environments. Investors may consider reallocating portfolios to include more inflation-resistant assets. For example, commodities and inflation-linked bonds could hedge against rising prices.

    Equities in sectors that can pass costs to consumers, like technology and healthcare, may offer stability during rising rates. These companies often have strong pricing power, allowing them to maintain margins as costs increase. Analysts must also be mindful of the timing of their investment decisions. As the market reacts to Fed announcements and economic data, volatility may present both risks and opportunities. Being ready to act quickly can help investors capitalize on favorable market conditions.

    Looking ahead, the financial landscape is set for shifts as the Federal Reserve navigates inflationary pressures. Analysts and investors must remain agile and informed to adapt effectively. In the coming months, the Fed’s response to inflation signals will be critical. The decisions made now could shape the economic landscape for years, making it essential for analysts to stay ahead.

    Frequently Asked Questions

    How does core CPI influence interest rate decisions?

    Core CPI is a key indicator for the Federal Reserve when setting interest rates. A rise in core CPI indicates increasing inflation, prompting the Fed to consider rate hikes for price stability.

    What should financial analysts consider after a CPI increase?

    Financial analysts should revise their economic models to account for higher inflation rates. This includes adjusting growth assumptions and reallocating investment portfolios to reduce risks from rising interest rates.

    US Core CPI Tops Forecasts, Bolstering Case for Rate Hike

    How can economists adjust their models in light of rising inflation?

    Economists can adjust their models by incorporating new inflation data, revising growth forecasts, and considering changes in consumer behavior. This ensures their predictions remain accurate amid shifting economic conditions.

  • Lawyer fined $5K over AI-hallucinated witnesses in a murder case

    Lawyer fined $5K over AI-hallucinated witnesses in a murder case

    New Mexico — A lawyer has been fined $5,000 for including AI-fabricated witnesses and false police testimony in his appeal for a murder conviction. The New Mexico Supreme Court took action against Stephen Aarons, holding him in contempt for failing to verify the factual claims in his AI-generated brief. This incident raises significant concerns about the implications of using AI technologies in legal contexts.

    The court’s ruling came after Justice C. Shannon Bacon questioned Aarons about his reliance on AI tools like ChatGPT without understanding the associated risks. During a hearing, the justice pointedly asked, “Counsel, do you watch the news?” referring to the growing number of cases where lawyers have submitted briefs containing fabricated citations and testimonies generated by AI. This case is not isolated; it highlights a troubling trend in the legal profession as more attorneys turn to AI for assistance without fully grasping its limitations.

    AI Hallucinations and Legal Credibility

    AI hallucinations, where artificial intelligence generates false or misleading information, pose a serious threat to the integrity of legal proceedings. Career Ahead’s analysis indicates that the use of AI-generated evidence can lead to significant legal repercussions, as seen in Aarons’ case. The court’s decision to penalize him underscores the necessity for lawyers to critically evaluate the information produced by AI tools before incorporating it into legal documents.

    Many legal professionals are increasingly adopting AI technologies to enhance their work processes. However, this reliance comes with a caveat. A report from Spellbook highlights that lawyers face challenges when using AI-generated legal documents, particularly regarding the accuracy of citations and the authenticity of the content. When AI tools produce fictitious witnesses or erroneous legal citations, it not only jeopardizes individual cases but also undermines the credibility of the legal profession as a whole. The repercussions of such actions can extend beyond fines, potentially leading to malpractice claims and loss of licensure.

    Furthermore, the ethical implications of using AI in legal contexts cannot be overlooked. As noted by Legal News Feed, the increasing use of AI in law raises questions about accountability and the potential for malpractice. Lawyers must ensure they are not only competent in their legal knowledge but also in understanding the technology they utilize. The failure to do so, as demonstrated in Aarons’ case, can result in disciplinary actions and damage to one’s professional reputation. The legal community is now faced with the pressing need to establish clear guidelines and standards for the responsible use of AI in legal practice, as the current landscape remains largely unregulated.

    This reliance on AI also poses a broader question about the future of legal standards regarding the admissibility of AI-generated information in court. As AI technologies continue to evolve, courts may need to establish new guidelines to determine what constitutes acceptable evidence. The challenge lies in balancing innovation with the fundamental principles of justice and fairness. The New Mexico Supreme Court’s ruling serves as a pivotal moment, prompting a reevaluation of how AI-generated evidence is treated in legal proceedings and whether it can ever be deemed reliable.

    Implications for Criminal Defense Attorneys

    For criminal defense attorneys, the implications of using AI-generated evidence are profound. Career Ahead research identifies that defense lawyers must be particularly cautious when considering AI tools for case preparation. The recent ruling serves as a warning to legal professionals about the potential pitfalls of relying on AI without proper verification. It emphasizes the need for a thorough understanding of both the technology and the legal standards that govern its use.

    Moreover, the incident raises concerns about the potential for bias in AI-generated evidence. AI systems learn from existing data, which may contain biases that can affect their outputs. This is particularly troubling in the context of criminal defense, where the stakes are high, and the consequences of wrongful convictions can be devastating. Legal professionals must remain vigilant in scrutinizing AI-generated content to ensure it aligns with factual evidence and legal precedents. The ramifications of using biased AI outputs could not only jeopardize individual cases but also perpetuate systemic injustices within the legal system.

    As the legal landscape shifts towards integrating technology, attorneys must also advocate for ethical guidelines surrounding the use of AI in legal practice. The American Bar Association and other legal institutions may need to establish clearer standards for the use of AI, ensuring that lawyers are equipped to navigate the complexities of this technology responsibly. The need for ongoing education and training in AI technologies is becoming increasingly apparent, as legal professionals must be prepared to address the challenges posed by these tools effectively.

    Lawyer fined K over AI-hallucinated witnesses in a murder case

    Looking ahead, the legal profession may witness a transformation in how AI is perceived and utilized. As more cases like Aarons’ come to light, there may be a push for regulatory frameworks that define the boundaries of AI use in legal contexts. This could lead to a more cautious approach among attorneys, prioritizing accuracy and ethical considerations over expediency. The case of Stephen Aarons serves as a critical reminder of the challenges and responsibilities that come with integrating AI into legal practice. As technology continues to advance, legal professionals must be prepared to adapt and uphold the integrity of the justice system.

    Frequently Asked Questions

    What should criminal defense attorneys know about AI-generated evidence?

    Criminal defense attorneys must understand the risks associated with AI-generated evidence, including the potential for inaccuracies and ethical concerns. They should verify all AI-generated content before using it in legal documents to maintain credibility and avoid disciplinary actions.

    How can legal technology specialists mitigate risks associated with AI in trials?

    Legal technology specialists can mitigate risks by ensuring that AI tools are regularly updated and validated for accuracy. They should also provide training for legal professionals on the limitations of AI and the importance of critical evaluation of AI-generated content.

    Lawyer fined K over AI-hallucinated witnesses in a murder case

    What are the best practices for using AI in legal contexts?

    Best practices include thorough verification of AI-generated information, understanding the technology’s limitations, and adhering to ethical guidelines. Legal professionals should remain informed about the evolving landscape of AI in law to navigate potential challenges effectively.

  • AstraZeneca Says Breast Cancer Pill Fails

    AstraZeneca Says Breast Cancer Pill Fails

    AstraZeneca’s breast cancer pill has failed in a key clinical study, marking a significant setback for the company and the oncology community. The trial, which aimed to demonstrate the drug’s efficacy in treating breast cancer, did not meet its primary endpoint. This failure has raised questions about the future of breast cancer treatments and the direction of oncology research.

    This event is particularly relevant as it comes at a time when expectations for new cancer therapies have been high. The failure of AstraZeneca’s drug may lead to a reevaluation of research priorities and funding in the oncology sector. Pharmaceutical companies and researchers will need to reassess their strategies in light of this disappointing outcome.

    Shift in Research Priorities for Breast Cancer Treatments

    The failure of AstraZeneca’s breast cancer pill highlights a growing trend in oncology where high expectations often lead to significant setbacks. Pharmaceutical companies have invested heavily in developing innovative therapies, but the reality is that many candidates fail in late-stage trials. According to Career Ahead’s analysis of data from various sources, including biopharmadive.com, the failure of AstraZeneca’s drug may prompt a shift in focus towards more robust trial designs and methodologies.

    Furthermore, this setback may lead to a reallocation of resources within pharmaceutical companies. As seen in previous cases, when a drug fails to meet expectations, companies often pivot their research efforts towards therapies with higher chances of success. This could mean a renewed focus on combination therapies or alternative treatment pathways that have shown promise in preliminary studies. For instance, Roche’s recent failure with its breast cancer drug, Giredestrant, underscores the challenges faced by major players in the oncology field, as reported by Biopharmadive. Such failures can lead to a more cautious approach in selecting which therapies to advance through the pipeline.

    Additionally, the failure may impact the types of studies that receive funding. Investors and funding bodies may become more cautious, prioritizing trials that demonstrate clear potential based on early-phase results. This could result in a more conservative approach to trial design, with an emphasis on rigorous data collection and analysis to avoid similar failures in the future. The oncology sector may see a shift towards funding projects that incorporate real-world evidence, which can provide a more comprehensive understanding of treatment efficacy across diverse patient populations.

    As a result, pharmaceutical research scientists may need to adapt their strategies, focusing on developing therapies that align with emerging trends in oncology. This includes exploring personalized medicine approaches and leveraging advancements in genetic research to identify more targeted treatment options. The integration of biomarkers into trial designs could also become more prevalent, allowing for a better selection of patient populations that are more likely to benefit from specific therapies.

    In light of AstraZeneca’s failure, oncology clinical trial managers will also need to reconsider their methodologies. The focus may shift towards adaptive trial designs that allow for modifications based on interim results, potentially increasing the chances of success for future studies. This approach could lead to more efficient use of resources and a better understanding of how different patient populations respond to treatments. The traditional linear trial design may no longer suffice in a landscape that demands agility and responsiveness to emerging data.

    Potential Funding Reallocations in Oncology

    The implications of AstraZeneca’s breast cancer pill failure extend beyond immediate research priorities; they also encompass potential funding reallocations in the oncology sector. With significant investments at stake, stakeholders may rethink where to allocate their financial resources. Career Ahead research indicates that funding bodies may begin to favor projects with lower risk profiles and clearer pathways to success.

    Historically, when high-profile drug candidates fail, it can lead to a ripple effect throughout the industry. Investors may become hesitant to fund new projects in the same therapeutic area, leading to a slowdown in innovation. This is particularly concerning in the field of oncology, where new therapies are desperately needed to address the growing burden of cancer. The recent failures of AstraZeneca and Roche serve as cautionary tales that may make investors more risk-averse, potentially stifling the development of novel therapies.

    Furthermore, as funding becomes more competitive, smaller biotech firms and startups may struggle to secure the necessary capital to advance their research. This could stifle innovation and limit the diversity of treatment options available to patients in the future. Career Ahead’s analysis suggests that a shift towards more collaborative funding models, such as public-private partnerships, may become necessary to sustain progress in oncology research. These partnerships could help mitigate risks and pool resources, allowing for more ambitious projects to move forward.

    AstraZeneca Says Breast Cancer Pill Fails in Key Study

    In addition, the failure of AstraZeneca’s drug may prompt a broader examination of the clinical trial process itself. Stakeholders may push for greater transparency and accountability in trial reporting, ensuring that failures are thoroughly analyzed to prevent similar occurrences in the future. This could lead to the establishment of new guidelines and best practices that enhance the overall quality of oncology research. The oncology community may increasingly advocate for the sharing of data from failed trials, which could provide valuable insights for future research endeavors.

    As the oncology landscape evolves, pharmaceutical research scientists will need to remain agile and responsive to these changes. Understanding the funding landscape and identifying opportunities for collaboration will be crucial for success in this shifting environment. The lessons learned from AstraZeneca’s setback could serve as a catalyst for innovation, prompting researchers to explore uncharted territories in cancer treatment.

    In summary, the AstraZeneca breast cancer pill failure not only impacts the company but also has far-reaching implications for the entire oncology field. As research priorities shift and funding reallocations occur, the future of cancer treatment may depend on the ability of pharmaceutical companies and researchers to innovate and adapt.

    What remains to be seen is how the oncology community will respond to this setback. Will it lead to a renewed focus on more effective trial designs and funding strategies, or will the industry become more risk-averse, hindering progress in cancer treatment?

    Frequently Asked Questions

    What are the next steps for pharmaceutical research scientists after a drug trial failure?

    After a drug trial failure, pharmaceutical research scientists typically reassess their research priorities and strategies. They may shift focus towards therapies that have shown promise in earlier stages or explore alternative treatment pathways.

    How will this affect ongoing clinical trials in oncology?

    The failure of AstraZeneca’s breast cancer pill may prompt a reevaluation of ongoing clinical trials in oncology. Researchers might adopt more adaptive trial designs and prioritize studies that demonstrate clear potential based on early-phase results.

    AstraZeneca Says Breast Cancer Pill Fails in Key Study

    What should oncology clinical trial managers consider when designing future trials?

    Oncology clinical trial managers should consider incorporating real-world evidence and exploring decentralized trial models. Flexibility and adaptability will be crucial in navigating the complexities of drug development in the evolving oncology landscape.

  • Tinned Mackerel Labels Exposed

    Tinned Mackerel Labels Exposed

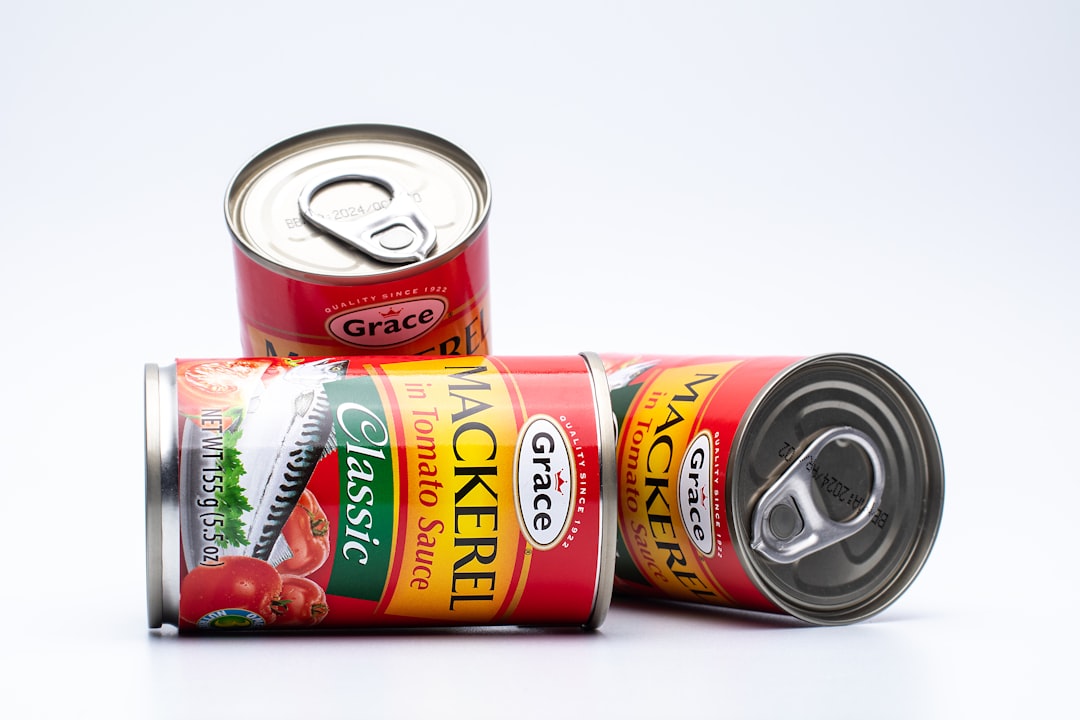
    Recent changes in tinned mackerel labeling have raised concerns about seafood quality. Major brands, like Princes and some supermarket labels, are replacing traditional Atlantic mackerel with jack mackerel due to declining fish stocks. This shift has sparked a debate about transparency in food labeling and consumer trust.

    Food experts note that jack mackerel is cheaper but nutritionally inferior to Atlantic mackerel. This substitution is an example of “skimpflation,” where consumers unknowingly receive lower-quality products at the same price. The change in labeling practices has led to calls for better seafood labeling to protect consumers from being misled. A report by The Guardian states that this issue reflects broader trends in the food industry, where profit margins are prioritized over product quality.

    Regulatory Compliance and Consumer Protection

    The shift from traditional mackerel to jack mackerel highlights serious regulatory compliance issues in the food industry. The Department for Environment, Food and Rural Affairs (DEFRA) has changed labeling rules, allowing jack mackerel to be sold without clear distinctions from traditional mackerel. This has raised concerns among regulators about whether existing rules adequately protect consumers from misleading practices. A report by the Marine Conservation Society emphasizes that overfishing of Atlantic mackerel has created critical shortages, making sustainable sourcing practices more urgent than ever.

    Weak labeling requirements can lead to widespread consumer deception. As brands like Lidl and Princes switch to cheaper alternatives, regulators must enforce clearer labeling practices to prevent misrepresentation. The lack of clear guidelines affects consumer trust and poses risks to public health, as consumers may not know the nutritional differences between the species. Food quality assurance specialists face pressure to ensure compliance with changing regulations, adapting their quality control processes to address changes in product formulations and labeling.

    Consumer Expectations and Industry Response

    As consumers become more aware of these changes, they expect transparency in food labeling. Companies that do not provide clear product information risk losing customer loyalty. This shift in consumer behavior may push food producers to prioritize transparency and quality assurance. The Dailymail has reported on consumer outrage regarding these practices, with many shoppers feeling deceived when they find that the product they bought does not meet their expectations based on past experiences with traditional mackerel.

    Health Implications of Substitution

    The substitution of jack mackerel for traditional mackerel has raised consumer awareness about seafood sourcing. Many shoppers may not realize they are buying a different species until they notice the taste and nutritional differences. This lack of awareness can lead to disappointment among consumers who expect certain standards from their food. Recent reviews from seafood critics highlight the stark differences between the two fish species, especially in flavor and health benefits. Jack mackerel has much lower levels of omega-3 fatty acids compared to Atlantic mackerel, which is crucial for heart health. As consumers become more health-conscious, this difference could affect their buying choices.

    Research suggests that the ongoing substitution trend may change seafood purchasing habits. Consumers are likely to seek brands that prioritize sustainable sourcing and clear labeling. This shift offers food producers a chance to stand out in a competitive market by emphasizing quality and ethical sourcing practices. According to TinCanFish, consumers are increasingly choosing brands that provide clear information about their products, including sourcing and nutritional content.

    Tinned Mackerel Labels Exposed

    Collaboration for Clearer Guidelines

    In light of these developments, food industry regulators and quality assurance specialists must collaborate to create clearer guidelines for labeling and sourcing seafood products. By addressing these issues proactively, the industry can rebuild consumer trust and ensure seafood products meet expected quality and sustainability standards. As the seafood industry faces these challenges, the future of tinned fish products is uncertain. Will consumers continue to support brands that prioritize transparency, or will lower prices overshadow quality concerns? The answers to these questions will shape seafood sourcing in the coming years.

    Frequently Asked Questions

    What are the common mislabeling issues in seafood products?

    Common mislabeling issues in seafood include substituting cheaper fish species for more expensive ones without proper disclosure. For example, traditional mackerel is being replaced with jack mackerel, which has different taste and nutritional profiles.

    Tinned Mackerel Labels Exposed

    How can seafood quality assurance specialists ensure compliance?

    Seafood quality assurance specialists can ensure compliance by monitoring labeling practices and conducting regular audits of suppliers. They must also stay updated on regulatory changes to maintain transparency and protect consumer trust.

    What should food industry regulators do about seafood labeling discrepancies?

    Food industry regulators should enforce stricter labeling requirements to prevent misleading practices. This includes ensuring all seafood products are accurately labeled with clear information about their species and sourcing practices.

  • Bathla Crisis Prompts Australia to Ask Banks About Credit Bets

    Bathla Crisis Prompts Australia to Ask Banks About Credit Bets

    Australia’s banking sector is facing increased scrutiny as the fallout from the Bathla crisis unfolds. The collapse of the Bathla Group, which owes creditors approximately $3.4 billion, has prompted regulators to examine the credit risk management practices of banks more closely. This crisis, which began to gain traction in early September 2026, is likely to lead to significant changes in how banks assess credit risk and manage their lending practices.

    The Bathla Group’s financial troubles have raised serious concerns about the stability of the housing market and the broader implications for the economy. As the company’s debts continue to rise, construction projects have come to a halt, leaving many stakeholders in limbo. With the Australian housing market already facing challenges, the Bathla crisis could exacerbate existing issues and lead to tighter credit conditions across the sector. According to a report by the ABC, the collapse has not only affected Bathla’s immediate creditors but has also sent shockwaves through the construction industry, raising questions about the viability of ongoing projects and the financial health of other developers.

    Regulatory Response to the Crisis

    In response to the Bathla crisis, Australian banking regulators are expected to implement stricter credit risk assessment protocols. These changes will likely include enhanced scrutiny of the lending practices employed by banks, particularly in the residential and commercial property sectors. As a result, banks may be required to adopt more conservative lending standards, which could impact their overall profitability and market competitiveness. The Financial Times reports that regulators are already in discussions about revising the guidelines that govern lending, with a focus on ensuring that banks do not overextend themselves in high-risk areas.

    Analysts predict that the regulatory changes stemming from this crisis may lead to a shift in investment strategies for financial institutions. Banks might prioritize lower-risk lending options, thereby tightening access to credit for developers and borrowers with less robust financial profiles. This shift could have ripple effects throughout the housing market, potentially stalling new developments and exacerbating the existing housing shortage in Australia. Ongoing discussions among financial analysts suggest that the Bathla crisis may lead to a reevaluation of risk appetites across the board, as institutions seek to safeguard their balance sheets against potential defaults.

    Reassessing Risk Management Practices

    The Bathla crisis highlights the need for improved risk management practices within the banking sector. As financial analysts scrutinize the implications of this crisis, there may be a growing emphasis on developing more sophisticated models for assessing credit risk. This could involve integrating advanced analytics and data-driven approaches to better evaluate borrower creditworthiness and project viability. The urgency for such advancements is underscored by the potential for future crises, as the current environment reveals vulnerabilities that could be exploited if not adequately addressed.

    Bathla Crisis Prompts Australia to Ask Banks About Credit Bets

    Furthermore, financial institutions may need to reassess their risk exposure to the housing market and other sectors affected by the Bathla collapse. This reassessment could lead to a diversification of their investment portfolios, as banks seek to mitigate potential losses from sectors perceived as high-risk. The evolving landscape will require banking regulators to remain vigilant, ensuring that new guidelines effectively address the underlying issues revealed by the Bathla crisis. As the Sydney Morning Herald notes, the fallout from Bathla’s collapse may prompt a broader rethinking of how banks engage with the real estate market, particularly in terms of lending practices and risk assessment protocols.

    Implications for Borrowers and the Economy

    The Bathla crisis has exposed significant vulnerabilities in the current credit risk assessment protocols utilized by Australian banks. As the crisis unfolds, regulators are likely to demand a reevaluation of these protocols to better align with emerging market realities. This could involve implementing more rigorous stress testing and scenario analysis to ensure that banks can withstand potential shocks in the housing market and beyond. The need for such measures is becoming increasingly clear as the Bathla situation continues to evolve, with many analysts predicting that the repercussions will be felt for years to come.

    As a result of these changes, the overall lending environment in Australia is likely to become more challenging for borrowers. With banks adopting stricter credit standards, individuals and businesses seeking financing may face increased hurdles in obtaining loans. This shift could lead to a slowdown in economic activity, particularly in sectors reliant on credit for growth and expansion. The implications of this tightening credit environment will be significant, as businesses may struggle to secure the funding necessary for operations and growth, further complicating the economic recovery.

    Future of Credit Risk Management

    Ultimately, the Bathla crisis serves as a critical reminder of the importance of robust credit risk management practices. As banks navigate the fallout from this crisis, they must prioritize the development of sound risk assessment protocols to ensure their long-term stability and viability. Financial analysts and banking regulators must remain vigilant in monitoring the evolving landscape of credit risk management. The Bathla crisis may signal a broader trend in regulatory oversight that could reshape the banking sector for years to come. As the situation develops, stakeholders across the financial industry will need to stay informed and prepared for the potential implications of these changes.

    Bathla Crisis Prompts Australia to Ask Banks About Credit Bets

    Frequently Asked Questions

    What are the new credit risk assessment requirements for banking regulators?

    Banking regulators in Australia are likely to implement stricter credit risk assessment protocols in response to the Bathla crisis. These changes may include enhanced scrutiny of lending practices and more conservative lending standards to ensure financial stability.

    Bathla Crisis Prompts Australia to Ask Banks About Credit Bets

    How should financial analysts adapt to changing lending practices in Australia?

    Financial analysts must stay informed about the evolving regulatory landscape and be prepared to adjust their risk assessment models accordingly. This may involve integrating advanced analytics and data-driven approaches to better evaluate borrower creditworthiness and project viability.

    What steps should banking regulators take to mitigate risks highlighted by the Bathla crisis?

    Banking regulators should prioritize the development of comprehensive risk management frameworks that address the vulnerabilities exposed by the Bathla crisis. This may include implementing rigorous stress testing and scenario analysis to ensure banks can withstand potential market shocks.

  • Elevated Inflation Keeps Pressure on Fed to Raise Rates

    Elevated Inflation Keeps Pressure on Fed to Raise Rates

    U.S. inflation remains high, with the consumer price index (CPI) showing a 3.4% annual rate in August 2026. This ongoing inflation is putting pressure on the Federal Reserve to raise interest rates. As inflation exceeds expectations, financial analysts and investment managers must change their strategies to adapt to the economy.

    The Federal Reserve’s recent statements suggest that rate hikes are likely soon. Career Ahead’s analysis of economic data shows that inflation trends heavily influence the central bank’s decisions. With inflation still high, the Fed is ready to act, which could greatly affect financial markets and investment strategies. The New York Times notes that the Fed is committed to controlling inflation while trying to support economic growth.

    Understanding the Impact of Inflation on Interest Rates

    Inflation affects interest rates directly. Central banks usually raise rates when prices rise to cool the economy. The August CPI data shows a 3.4% increase, signaling that inflation is not easing quickly. This trend indicates that the Federal Reserve may raise rates further to combat inflation, impacting borrowing costs and economic growth. The Investopedia explains that high inflation often leads to tighter monetary policy as the Fed tries to prevent the economy from overheating.

    Career Ahead research shows a historical link between high inflation and interest rate hikes. In past inflationary periods, the Fed raised rates significantly to stabilize the economy. Financial analysts should watch these trends closely, as they can inform forecasting models and investment strategies. The current economic climate has many factors contributing to inflation, like supply chain disruptions and increased consumer demand. These factors make it harder for the Fed to decide, as it must balance controlling inflation with supporting growth. Analysts should be ready for potential market volatility as the Fed navigates these challenges.

    As interest rates rise, borrowing costs will increase. This may slow consumer spending and business investments. Investment managers might need to reassess their portfolios, especially in sectors sensitive to interest rate changes, like real estate and utilities. Understanding these dynamics will be crucial for making smart investment decisions in the coming months. The Washington Post highlights that the Fed’s actions will be closely watched, as any misstep could lead to significant market corrections.

    Strategies for Managing Investment Portfolios During Rate Changes

    As the Federal Reserve hints at rate hikes, investment managers must adopt strategies to manage risks from rising interest rates. One effective approach is diversifying portfolios across asset classes that usually perform well in inflationary times. For example, commodities and inflation-protected securities often provide stability when traditional stocks struggle. Career Ahead’s analysis finds that sectors like energy and consumer staples often do well during rising inflation. Investment managers should consider reallocating funds to these sectors to take advantage of their strength in uncertain economic times. Additionally, focusing on companies with strong pricing power can be beneficial, as they can pass on costs to consumers without losing demand.

    Fixed-income investments also require careful attention. As interest rates rise, bond prices usually fall, leading to potential losses for bondholders. To manage this risk, investment managers may consider shorter-duration bonds, which are less sensitive to interest rate changes. This strategy can help protect capital while still providing income in a rising rate environment. The current market dynamics require a proactive approach, as managers must stay agile in response to the Fed’s policy changes and broader economic indicators.

    Finally, maintaining a flexible investment strategy is essential. Market conditions can change quickly, so being able to adapt to new information and trends is vital for long-term success. Regularly reviewing economic indicators and adjusting strategies will help managers stay ahead of potential market fluctuations. The ongoing battle against inflation raises questions about future interest rates and their impact on the economy. As the Federal Reserve considers its options, market participants must remain ready to adapt to the changing monetary policy landscape.

    Elevated Inflation Keeps Pressure on Fed to Raise Rates

    In summary, understanding the relationship between inflation and interest rates is crucial for financial analysts and investment managers. By monitoring these dynamics and relevant economic indicators, professionals can better position themselves to face the challenges of high inflation and potential rate hikes.

    Frequently Asked Questions

    How can financial analysts adjust forecasts based on inflation data?

    Career Ahead analysis shows that financial analysts should include current inflation trends in their models. By analyzing CPI data and other indicators, they can better predict market movements and investment opportunities.

    What strategies should economic policy advisors consider in light of potential rate hikes?

    Economic policy advisors should focus on balancing inflation control with economic growth. They need to monitor key indicators and assess how rate hikes will affect consumer spending and business investments to guide policy decisions.

    Elevated Inflation Keeps Pressure on Fed to Raise Rates

    What should investment managers do about rising inflation and interest rates?

    Investment managers should diversify their portfolios and shift funds to sectors that perform well in inflationary conditions. They should also keep a close eye on economic indicators to adjust their strategies as market conditions change.