Tag: consumer behavior

  • Why Stricter Return Policies Hurt Retailers and Customers

    Why Stricter Return Policies Hurt Retailers and Customers

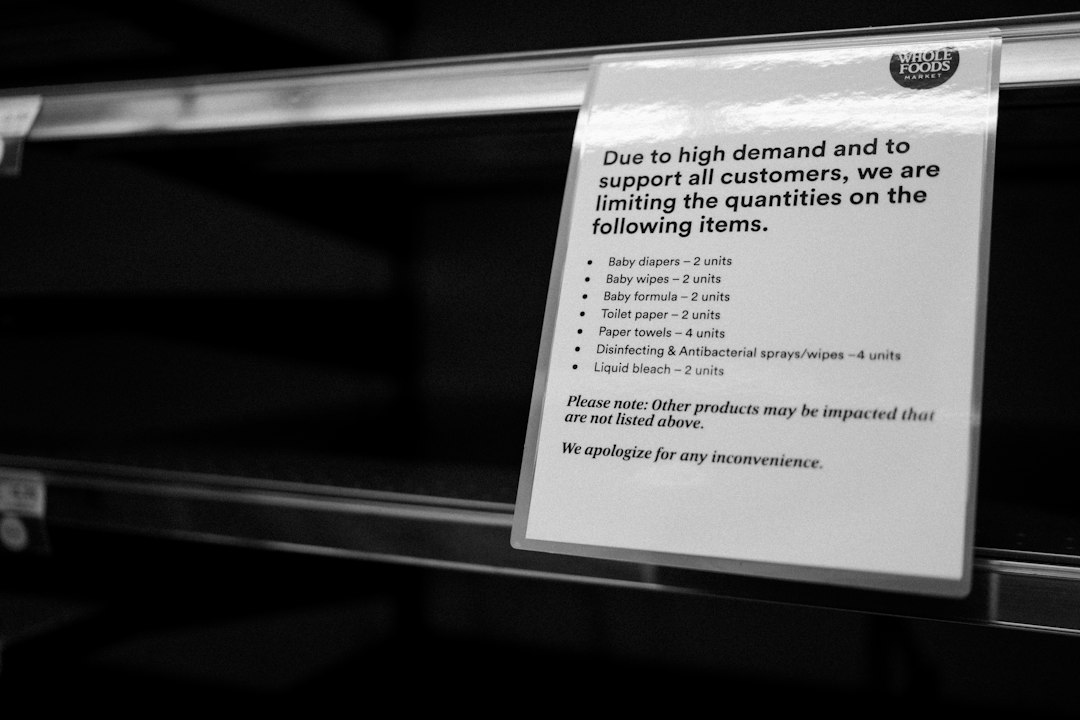
    Retailers across the United States are tightening return policies, leading to frustration among consumers. Reports indicate that customers are facing surprise fees, shorter return windows, and increased scrutiny over their reasons for returning items. This trend raises concerns about its long-term effects on customer loyalty and sales.

    The shift toward stricter return policies is particularly evident in the ecommerce sector. A report from the Wall Street Journal reveals that customers are unhappy with the challenges of returning items, with many receiving warnings that their future returns may not be accepted, which can push them away from brands entirely.

    Return Policies and Consumer Behavior

    Return policies significantly influence consumer decision-making. An analysis by Makemyreceipt.com found that 30% of consumers check a retailer’s return policy before making a purchase. When policies appear unfavorable, customers often abandon their carts or opt for competitors with more favorable terms. This trend is especially pronounced among younger shoppers who prioritize flexibility and ease.

    Retailers with strict return policies risk damaging their brand reputation. Negative experiences with returns can lead to bad reviews and social media backlash. In today’s fast-paced information environment, a single negative experience can deter potential customers and harm a retailer’s image.

    Conversely, businesses that adopt customer-friendly return policies often enjoy increased loyalty. Companies like Zappos thrive on hassle-free returns, resulting in higher customer satisfaction and repeat purchases. This approach enhances the shopping experience and builds trust between retailers and consumers.

    Retailers should focus on the long-term benefits of customer loyalty rather than short-term cost savings. Jerry Crawford, a successful carpet seller, exemplified this approach by setting aside a small percentage of his sales for potential returns, integrating this cost into his pricing strategy without alienating customers.

    Enhancing the Return Experience

    To improve customer satisfaction, retailers need to rethink their return processes. Simplifying returns can greatly enhance customer perceptions. This includes offering free returns, extending return windows, and minimizing questions during the return process. Such changes can foster a positive shopping environment that encourages repeat business.

    Technology can also play a vital role in streamlining returns. Online return portals and self-service options can reduce friction for customers. According to Worldmetrics.org, retailers that leverage technology for returns see a 15% increase in customer satisfaction, a significant advantage in a competitive market where customer experience is paramount.

    Moreover, training staff on the importance of customer service during returns is crucial. Employees should handle returns with empathy and efficiency, ensuring customers feel valued even when returning products. This personal touch can significantly impact customer perceptions and future purchases.
    Why Stricter Return Policies Hurt Retailers and Customers

    Finally, retailers should analyze return data to identify trends and issues. Understanding the reasons behind returns helps businesses make informed decisions about product quality and customer preferences, ultimately leading to better product offerings and reduced returns.

    Lessons from a Carpet Seller

    The story of Jerry Crawford illustrates the benefits of a thoughtful return strategy. Crawford’s business model included reserving a portion of sales for potential returns, allowing him to maintain a customer-friendly policy without sacrificing profitability. His strategy not only satisfied customers but also built a loyal client base that returned for future purchases.

    Crawford’s experience underscores the importance of viewing returns as a normal part of business rather than a burden. By accepting returns as an expected cost, retailers can create a more welcoming shopping environment. This mindset shift can lead to greater customer satisfaction and loyalty, driving sales growth.

    As retailers navigate challenges with return policies, they can learn from Crawford’s approach. Prioritizing customer satisfaction over strict policies can yield positive outcomes for both customers and businesses.

    Adapting to Consumer Expectations

    The retail industry must adapt to changing consumer expectations, especially as online shopping continues to grow. The demand for flexible return policies is likely to rise, and retailers who recognize this trend and act accordingly will likely thrive in a competitive landscape.

    Frequently Asked Questions

    What are best practices for return policies in retail?

    Best practices for return policies include offering free returns, extending return windows, and minimizing customer friction. Retailers should focus on creating a seamless experience to enhance customer satisfaction.

    Why Stricter Return Policies Hurt Retailers and Customers

    How do return policies affect ecommerce sales?

    Strict return policies can negatively impact ecommerce sales, as customers are less likely to complete purchases if they find return policies unfavorable, leading to higher cart abandonment rates.

    What should retail managers consider when implementing stricter return policies?

    Retail managers should weigh the potential loss of customer loyalty against the perceived benefits of stricter return policies. Understanding customer expectations and the long-term impact on brand reputation is essential for making informed decisions.
  • Rising fuel costs hitting businesses and customers

    Rising fuel costs hitting businesses and customers

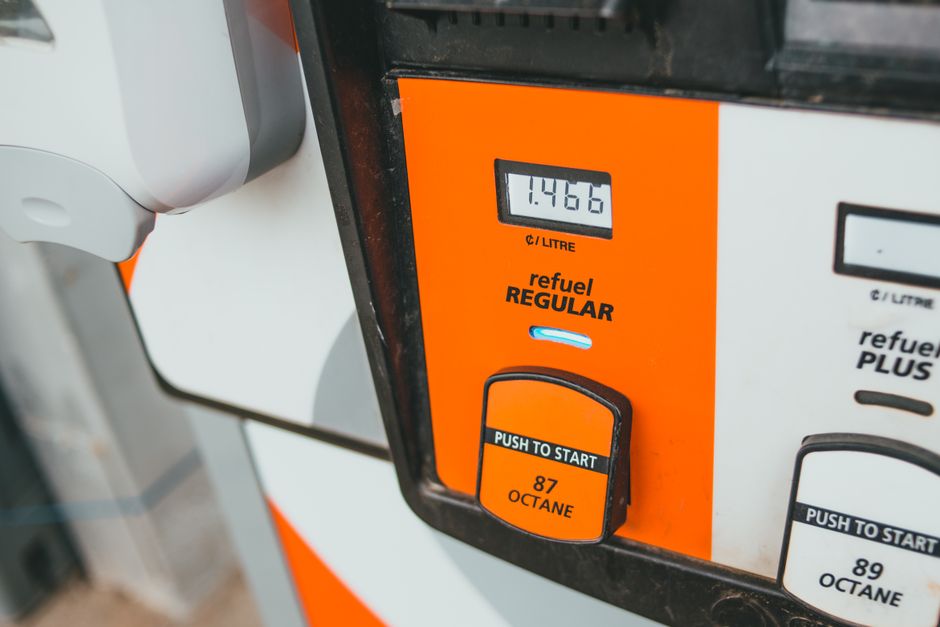
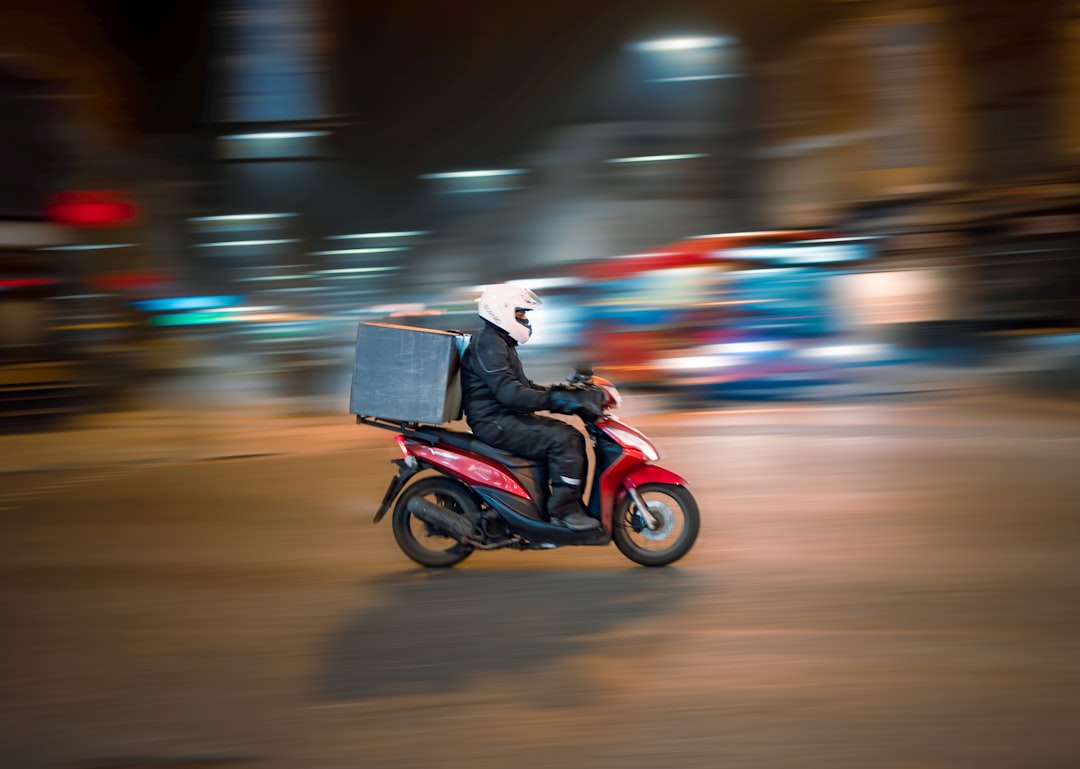
    Cornwall, UK — Rising fuel costs are significantly impacting independent businesses and delivery drivers in Hayle, with petrol prices averaging 161.3p per litre and diesel expected to exceed £2 per litre. This surge in fuel prices is forcing local businesses to adjust their delivery operations and consumers to rethink their spending habits.

    The increase in fuel prices has affected various sectors in Hayle, particularly those reliant on delivery services and tourism. Mark Nicholas, owner of The Big Pink Tree, a local flower shop, mentioned that the rising costs have limited the distance they can deliver, directly impacting their customer base. He stated, “The fuel increase has really affected how far we can deliver to serve our customer base.” This sentiment is echoed across multiple businesses in the area, indicating a broader trend of operational strain.

    Delivery Costs and Business Operations

    Delivery costs are a critical component for independent businesses, especially in regions like Cornwall, where distances can be significant. As fuel prices rise, businesses face higher transportation costs, which can erode profit margins. Local businesses may have to pass on these costs to customers, potentially deterring spending.

    Justin Lapskas, manager of Down the Line Surf Shop, noted that the higher fuel prices affect the import and transportation of products. He explained, “We bring in products from around the world, so for us, the increase in fuel prices has an effect and something that we’ve kind of got to deal with moving forward.” This situation forces businesses to reassess their logistics and delivery strategies to maintain profitability.

    Moreover, the rising fuel costs are not only affecting delivery operations but also the frequency with which customers engage with local businesses. Emma Crossley, a local hairdresser, observed that clients are waiting longer between appointments due to the increased travel costs. She stated, “Since the fuel prices went up, I have noticed a difference in how often people have their hair done. About five years ago, it would have been about six or seven weeks — now it’s more like 10 to 12 weeks.” This change in consumer behavior indicates a shift towards more cautious spending.

    Consumer Spending Trends Amid Rising Costs

    The rising fuel prices are leading to noticeable changes in consumer behavior. As costs increase, consumers are becoming more selective about their purchases, often opting for essential items over discretionary spending. This trend is particularly concerning for businesses that rely on tourism, which is a significant part of Cornwall’s economy.

    Tourism operators have reported a decline in bookings as potential visitors reconsider their travel plans. Pauline Ellis, who runs a bed and breakfast, mentioned that some visitors have canceled trips due to the high travel costs. She stated, “We are a long way down here, and I think it has made an impact on whether people can afford to come this far down, with the prices as they are.” This sentiment reflects a broader concern for the future of tourism in the region.

    Additionally, local residents are feeling the pinch, with many reconsidering their travel habits. One resident, who drives an eight-mile round trip daily, expressed frustration with the rising costs, stating that fuel prices have become “extortionate.” This shift in consumer sentiment could lead to long-term changes in how residents and visitors interact with local businesses.

    Rising fuel costs hitting businesses and customers

    Strategies for Business Adaptation

    In response to these challenges, independent businesses in Cornwall must adapt to the new economic realities. Research indicates that businesses that can streamline their operations and find cost-effective delivery solutions will be better positioned to weather these challenges. This includes exploring local sourcing options to minimize transportation needs and investing in more efficient delivery methods.

    Moreover, businesses focusing on innovative logistics can mitigate the impact of rising costs. For instance, those who adapt quickly may find new avenues for growth even in a challenging economic climate. Offering promotions, loyalty programs, or emphasizing local products can help attract customers who are more cautious with their spending.

    Long-Term Implications for Cornwall’s Economy

    The implications of rising fuel costs extend beyond immediate financial pressures. As consumers and businesses adjust to this new reality, the long-term effects on Cornwall’s economy and its independent businesses will become clearer. The coming months will be critical in determining how these entities navigate the challenges posed by rising fuel prices.

    Rising fuel costs hitting businesses and customers

    The tourism sector, in particular, faces an uphill battle as it attempts to recover from the impacts of the pandemic while now contending with the additional burden of high fuel costs. Local businesses that cater to tourists, such as restaurants, shops, and accommodations, are already feeling the impact. Reports indicate that many have seen a decline in foot traffic and bookings this season. As the situation evolves, the resilience of Cornwall’s independent businesses and tourism operators will be tested. How they adapt to these fuel price increases will determine their ability to thrive in a changing economic environment.

    Rising fuel costs hitting businesses and customers

    Frequently Asked Questions

    How can independent business owners mitigate rising delivery costs?

    Independent business owners can explore local sourcing options to reduce transportation needs and consider investing in more efficient delivery methods. Additionally, they can streamline operations to cut unnecessary expenses.

    What strategies can delivery drivers use to cope with increased fuel prices?

    Delivery drivers can optimize their routes to minimize fuel consumption and consider carpooling or sharing deliveries with other drivers to reduce costs. Staying informed about fuel-efficient driving techniques can also help save money.

    What should independent businesses do to adapt to changing consumer spending due to fuel costs?

    Independent businesses should innovate their marketing strategies, such as offering promotions or emphasizing local products. Understanding consumer behavior shifts will help them tailor their offerings to meet changing demands.

  • Fed Raises Rates in First Major Step | Career Outlook

    Fed Raises Rates in First Major Step | Career Outlook

    The Federal Reserve raised interest rates for the first time since July 2023 on September 16, 2026. This decision aims to curb inflation. Governor Warsh led this move just weeks before the midterm elections. It is expected to have significant effects on various sectors of the economy.

    This rate hike is crucial for financial analysts, real estate investors, and small business owners. As borrowing costs rise, understanding these changes is essential for making informed investment and financing decisions.

    Impact on Real Estate Investments

    The recent interest rate increase will directly affect mortgage rates. Lenders will likely adjust to the new benchmark, causing mortgage rates to rise. Higher rates can decrease housing demand, as potential buyers may struggle with monthly payments. Career Ahead’s analysis shows that a 1% increase in mortgage rates can reduce home affordability by about 10%. This makes it harder for first-time buyers to enter the market.

    Real estate investors should also consider the impact on property values. As borrowing costs rise, overall demand for properties may decline. This could slow price growth or even decrease property values. Investors who are heavily leveraged may face refinancing challenges. If their rental income does not cover increased debt service, they could be in a tough spot. According to USA Today, the Fed’s decision to raise rates could cool the housing market. Many analysts predict a slowdown in home sales as buyers retreat due to higher costs.

    The commercial real estate sector may also see changes. Businesses may reassess their expansion plans because of increased financing costs. Investors in commercial properties should prepare for a potential slowdown in leasing activity. Career Ahead research indicates that sectors reliant on borrowing, like retail and hospitality, may be particularly vulnerable. The Guardian highlights that businesses facing higher costs may delay or scale back their expansion plans, further impacting demand for commercial properties.

    In summary, real estate investors need to be proactive as the landscape shifts. Those considering new investments should conduct thorough market analyses. They should also be ready for a longer timeline for returns as the market adjusts to higher interest rates. The overall market sentiment may shift towards a more cautious approach, requiring investors to weigh financing risks in a high-rate environment.

    Changes in Consumer Spending Behavior

    Higher borrowing costs will likely change consumer spending patterns, affecting various sectors. As interest rates climb, consumers may focus on paying down existing debt instead of making new purchases or loans. This shift can lead to reduced sales for retailers and service providers, especially those relying on credit.

    Career Ahead’s analysis finds that discretionary spending is sensitive to interest rate changes. As consumers face higher costs for mortgages and loans, they may cut back on non-essential items. This will affect industries like travel, luxury goods, and dining out. Retailers and service providers should prepare for a potential decline in consumer spending and adjust their strategies. AP News reports that sectors like travel and hospitality may see a downturn as consumers become more cautious, opting for savings over discretionary purchases.

    Additionally, the interest rate increase may lead consumers to be more cautious about large purchases, such as vehicles and appliances. This could slow growth in sectors that depend on consumer financing, further impacting overall economic growth. Businesses that adapt to changing consumer preferences and offer flexible payment options may find opportunities even in a tightening market. Analysts from The Guardian suggest that the economic environment may shift towards one where consumers prioritize savings and debt repayment, significantly impacting retail sales and service industries.

    Fed Raises Rates in First Major Step | Career Outlook

    Financial analysts must monitor these changes closely. Shifts in consumer behavior can significantly affect corporate earnings and stock prices. Understanding how different sectors respond to these economic changes will be crucial for informed investment decisions. The interplay between rising rates and consumer confidence will be a key area for analysts. Any significant downturn in spending could have broader implications for economic recovery.

    In light of these developments, financial analysts and investors must remain vigilant and adaptable. Navigating the implications of the Fed’s interest rate hike is crucial. The economic landscape is shifting, and those who can anticipate these changes will be better positioned to succeed.

    Frequently Asked Questions

    How will rising interest rates impact my mortgage rates?

    Career Ahead’s analysis shows that rising interest rates will lead to higher mortgage rates. This makes home financing more expensive. A 1% increase in rates can reduce home affordability by about 10%, impacting potential buyers’ purchasing power.

    What should real estate investors consider with the Fed’s rate hike?

    Real estate investors need to assess how higher borrowing costs will affect property values and demand. With increased mortgage rates, investors should prepare for a slower market and reconsider their investment strategies.

    Fed Raises Rates in First Major Step | Career Outlook

    How can small business owners prepare for increased borrowing costs?

    Small business owners should evaluate their financing options and consider alternative sources of capital, like equity financing. Additionally, managing cash flow effectively will be crucial to navigate the challenges posed by rising interest rates.

  • Parliament Committee Overlooks MDR Charges on UPI Transactions

    Parliament Committee Overlooks MDR Charges on UPI Transactions

    India’s Parliament Standing Committee recently did not discuss the Merchant Discount Rate (MDR) charges on Unified Payments Interface (UPI) transactions, according to Gaurav Gogoi, a prominent member of the committee. This omission is raising eyebrows among fintech professionals and analysts, as it could have far-reaching implications for digital payment systems in the country.

    The absence of discussion on MDR charges comes at a time when the UPI has become a cornerstone of digital transactions in India. The platform has seen exponential growth, with over 45 billion transactions recorded in the last fiscal year alone. The lack of regulatory clarity on MDR could hinder the growth trajectory of fintech companies that rely heavily on UPI for their operations.

    Implications of MDR Charges on UPI Transactions

    Merchant Discount Rate (MDR) is the fee that merchants pay to banks or payment service providers for processing transactions. Currently, UPI transactions are largely free for consumers, which has contributed to its rapid adoption. However, if MDR charges are imposed, it could lead to increased costs for merchants, which may, in turn, be passed on to consumers. This potential increase in transaction costs could deter users from adopting UPI for smaller transactions, which are crucial for the platform’s widespread usage.

    Career Ahead’s analysis finds that the imposition of MDR could lead to a significant shift in consumer behavior. If transaction fees are introduced, users may opt for cash transactions or look for alternative payment methods that do not incur additional costs. This shift could undermine the very goals of the Digital India initiative, which aims to promote cashless transactions.

    Furthermore, the lack of discussion on MDR charges indicates a broader issue of regulatory oversight in the fintech sector. According to elibrary.sansad.in, the absence of clear guidelines could create an uncertain environment for fintech companies, making it difficult for them to plan their business strategies effectively. This uncertainty could lead to a slowdown in innovation and investment in the sector.

    The implications of MDR charges extend beyond just transaction costs. They could also affect the competitive landscape among fintech companies. Established players may have the resources to absorb these costs, while smaller startups could struggle to remain viable. This could stifle competition and limit consumer choices in the long run.

    Regulatory Implications for Fintech Companies

    The oversight by the Parliament Standing Committee highlights the need for a more robust regulatory framework for fintech companies. Currently, many fintech firms operate in a gray area, with regulations that are either outdated or non-existent. The lack of discussion on MDR charges suggests that lawmakers may not fully understand the complexities of the digital payments ecosystem.

    According to vajiramandravi.com, the evolution of fintech regulations is crucial for fostering a healthy environment for innovation. Without clear regulations, fintech companies may face challenges in compliance, which could lead to legal issues and reputational damage. A well-defined regulatory framework would not only help in managing risks but also encourage responsible innovation.

    Career Ahead research identifies that a lack of regulatory clarity can deter foreign investment in the Indian fintech sector. Investors seek environments where rules are transparent and predictable. The uncertainty surrounding MDR charges could lead potential investors to reconsider their strategies in the Indian market.

    Parliament Committee Overlooks MDR Charges on UPI Transactions

    Moreover, the absence of regulatory discussions on MDR could also impact partnerships between fintech companies and traditional financial institutions. Banks may be hesitant to collaborate with fintech firms if they are unsure about the regulatory landscape, thereby limiting opportunities for innovation and growth.

    As the fintech landscape evolves, it is crucial for regulators to engage in meaningful dialogue with industry stakeholders. This collaboration can help create policies that are not only effective but also promote growth and innovation in the sector.

    Potential Changes in Consumer Behavior Regarding Digital Payments

    The lack of clarity around MDR charges may lead to changes in how consumers perceive and use digital payment systems. If consumers begin to associate UPI with additional costs, their willingness to adopt and use the platform may decline. This shift could have significant repercussions for the digital payments ecosystem, which has thrived on the premise of low-cost or free transactions.

    Career Ahead’s analysis shows that consumer behavior is highly sensitive to transaction costs. If users feel that UPI transactions are becoming too expensive, they may revert to cash or seek alternative payment methods, such as digital wallets that do not impose similar fees. This change could undermine the UPI’s position as a leading payment method in India.

    Additionally, the introduction of MDR charges could lead to a segmentation of users based on transaction size. High-value transactions may continue to utilize UPI, while low-value transactions could see a significant drop. This segmentation could create a bifurcated market where only certain demographics benefit from the advantages of UPI.

    Parliament Committee Overlooks MDR Charges on UPI Transactions

    Moreover, as digital literacy improves and more consumers become aware of their options, the demand for transparency in transaction costs will increase. Consumers will likely seek platforms that offer clear pricing structures and no hidden fees. Fintech companies that fail to adapt to these changing consumer expectations may find themselves at a disadvantage.

    The future of UPI and other digital payment systems hinges on how regulators and fintech companies respond to these challenges. As the landscape evolves, stakeholders must remain vigilant and adaptable to ensure the continued growth of digital payments in India.

    The Parliament Standing Committee’s failure to discuss MDR charges raises critical questions about the future of digital payments in India. As the regulatory landscape remains unclear, the potential for significant shifts in consumer behavior looms large, making it essential for stakeholders to engage in proactive discussions.

    Frequently Asked Questions

    What are MDR charges and how do they affect UPI transactions?

    MDR charges are fees that merchants pay to banks for processing transactions. If imposed on UPI transactions, they could lead to increased costs for consumers and affect adoption rates.

    How can fintech companies prepare for potential changes in MDR regulations?

    Fintech companies should closely monitor regulatory developments and engage with policymakers to advocate for favorable terms that support innovation and growth.

    Parliament Committee Overlooks MDR Charges on UPI Transactions

    What should fintech product managers do about the lack of discussion on MDR charges?

    Fintech product managers should analyze the potential impacts of MDR charges on their business models and prepare strategies to adapt to changing consumer behaviors and regulatory landscapes.