Category: Career Tips

  • Build Your Credit Score After Your First Job

    Build Your Credit Score After Your First Job

    Starting your first job at 21 can be exciting but also overwhelming. For many young professionals, this milestone marks the start of building a credit score. A good credit history is vital for future financial opportunities, like loans for cars or homes. Career Ahead’s analysis shows that young adults can build credit without taking on unnecessary debt.

    Many recent graduates may not realize how important their credit score is until they need to make big purchases. Establishing a responsible credit track record early can make it easier to access credit later. Using manageable credit products wisely is key to building a strong credit profile.

    Understanding Credit Scores and Their Importance

    A credit score is a number that shows an individual’s creditworthiness. It is based on credit history, including payment history, credit utilization, and types of credit accounts. For young professionals, a good credit score can lead to better loan terms, lower interest rates, and even job opportunities in some fields.

    Research from the US Chamber of Commerce shows that about 70% of employers check credit scores during hiring. This trend highlights the importance of maintaining a good credit score early in one’s career. Young professionals who build their credit scores may have an advantage when applying for jobs or loans. A strong credit score can also influence loan terms, potentially saving them thousands in interest payments over time.

    Building a credit score early can help young adults avoid challenges later in life. Career Ahead’s analysis notes that individuals with a solid credit history are more likely to receive favorable loan and credit card terms. This can lead to significant savings over time. It is crucial for recent graduates to prioritize their credit-building efforts. Understanding the factors that influence credit scores can help young professionals make informed financial decisions. By focusing on timely payments and responsible credit use, they can ensure their credit scores reflect their reliability.

    Young adults should also know that credit scores are not static; they can change based on financial behavior. A single late payment can hurt a credit score, while consistent on-time payments can improve it. Therefore, a proactive approach to credit management is essential for long-term success.

    Effective Strategies for Building Credit Without Debt

    One effective way for young professionals to build credit is by starting with a secured credit card. This card requires a cash deposit as collateral, making it easier for those with no credit history to qualify. Experts recommend using a secured credit card for regular expenses and paying the balance in full each month. This helps establish a positive credit history and encourages financial discipline.

    Career Ahead research shows that using credit responsibly is more important than the number of credit products one has. Young professionals should focus on using their credit card for manageable expenses, like groceries or gas, and pay off the balance on time. This approach builds credit and fosters healthy financial habits. Additionally, young adults should keep their credit utilization ratio low—ideally below 30% of their available credit limit—as this is a key factor in credit scoring.

    Another option for recent graduates is to become an authorized user on a family member’s credit card. This allows them to benefit from the primary cardholder’s credit history without being responsible for payments. It can help build a credit profile while minimizing financial risk. However, it is essential to choose a responsible primary cardholder, as their behavior will impact the young professional’s credit score.
    Build Your Credit Score After Your First Job

    Young professionals can also explore alternative credit-building options, like credit-builder loans. These loans are designed for individuals looking to establish or improve their credit scores. By making regular payments, graduates can show lenders their creditworthiness. This method can be especially beneficial for those without access to traditional credit products.

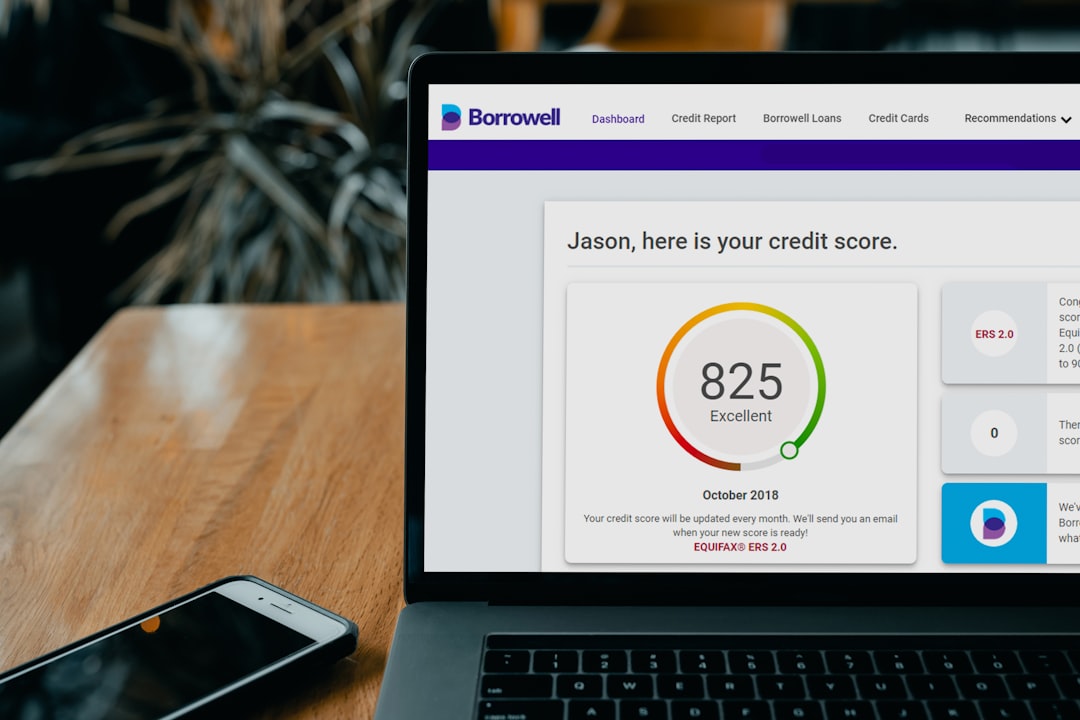
    Once a young professional starts building credit, monitoring their credit score regularly is essential. Many financial institutions and credit bureaus offer free credit monitoring services. These services allow individuals to track their credit scores and receive alerts about changes. This proactive approach can help identify potential issues before they become significant problems. Career Ahead’s analysis finds that many young adults are unaware of how their financial habits affect their credit scores. For example, maintaining a low credit utilization ratio—ideally below 30%—can positively impact credit scores. Young professionals should keep their credit card balances low relative to their limits.

    Being mindful of payment due dates is also crucial. Setting up reminders or automatic payments can help ensure bills are paid on time. Consistent on-time payments are one of the most significant factors in determining creditworthiness. In addition to monitoring credit scores, young professionals should be cautious about applying for new credit. Each new credit application results in a hard inquiry on the credit report, which can temporarily lower the credit score. Therefore, it is wise to limit new credit applications and only apply when necessary.

    Overall, building a strong credit score as a recent graduate is possible and essential for long-term financial health. By starting early and using credit responsibly, young professionals can set themselves up for success. The habits they establish now will help them navigate larger financial decisions in the future. As the financial landscape evolves, recent graduates must stay informed about credit management. The strategies they adopt today can significantly impact their future borrowing power and overall financial stability. With the right approach, they can build a solid credit foundation that benefits them for years.

    Frequently Asked Questions

    How can recent graduates build credit without a credit card?

    Recent graduates can build credit without a credit card by using secured credit cards, becoming authorized users on family accounts, or taking out credit-builder loans. These options help establish a credit history while managing financial risk.

    What are the best practices for young professionals to manage their finances?

    Young professionals should focus on timely payments, maintaining low credit utilization, and regularly monitoring their credit scores. Establishing good financial habits early can lead to a stronger credit profile and better financial opportunities in the future.
    Build Your Credit Score After Your First Job

    What should recent graduates do about building credit before applying for loans?

    Before applying for loans, recent graduates should ensure they have a positive credit history by making timely payments on existing credit accounts. They can also consider using credit-building tools and monitoring their credit scores to prepare for future borrowing.
  • The job interview question you don't have to answer

    The job interview question you don't have to answer

    UK job applicants do not have to share their current salary during interviews. This change helps candidates negotiate better offers and protects their privacy. As salary transparency discussions grow, knowing these rights is vital for effective negotiations.

    Recently, there has been a renewed focus on salary disclosure practices in job interviews. Employers can ask about an applicant’s salary history, but candidates can choose not to answer. This shift emphasizes the need for negotiation skills and the importance of being informed about rights. According to a BBC News report, while employers can ask about salary history, applicants are not required to provide this information. This allows them to control their financial narratives.

    Legal Rights of Applicants Regarding Salary Questions

    In the UK, no laws prevent employers from asking about salary history. However, candidates do not have to disclose this information. Louise Rudd, a senior adviser at Acas, notes that applicants can decline to answer if they feel uncomfortable. This allows candidates to focus on their skills and qualifications instead of past salaries. Refusing to disclose salary history is especially important in a job market where candidates are more aware of their worth and potential wage gaps.

    The campaign to end salary history inquiries is gaining support. Organizations like the Fawcett Society advocate for change, arguing that these questions perpetuate wage disparities based on gender, race, and disability. By not disclosing past salaries, candidates can negotiate based on their worth instead of historical pay. Furthermore, new EU regulations will ban salary history inquiries, reflecting a trend toward salary transparency. While the UK has not yet adopted similar laws, ongoing discussions may lead to changes in salary negotiation practices. This evolving landscape is crucial for job seekers who want fair and equitable compensation.

    Career Ahead’s analysis shows that knowing one’s rights regarding salary disclosure can impact negotiation strategies. Being informed allows candidates to navigate discussions confidently and advocate for fair compensation based on their skills and experience. As more candidates refuse to disclose their salary history, employers may need to adjust their hiring practices, leading to a more equitable job market.

    As the job market evolves, applicants must stay informed about their rights and the implications of salary questions. This knowledge empowers them during interviews and contributes to a broader movement for equitable pay practices. The conversation around salary disclosure is not just about individual negotiations; it reflects larger societal issues of pay equity and fairness in the workplace.

    Impact on Salary Negotiation Strategies

    The ability to refuse salary disclosure can greatly influence how candidates negotiate. When applicants are not tied to past salaries, they can focus on the value they bring to potential employers. This shift encourages merit-based discussions rather than those rooted in historical pay. Shazia Ejaz, director of campaigns at the Recruitment and Employment Confederation, suggests that candidates should research market rates for their roles. This preparation helps them confidently articulate their worth, focusing on skills and contributions instead of previous earnings.

    Moreover, candidates can use their understanding of the salary range for the position to set expectations. Being well-informed allows them to negotiate from a position of strength, ensuring they receive compensation that reflects their abilities and market value. Career Ahead research indicates that job seekers who approach salary discussions with confidence and preparation are more likely to achieve favorable outcomes. This proactive approach benefits individuals and sets a precedent for future salary negotiations in their industry. Effective negotiation can lead to better job satisfaction and retention rates, as employees feel valued for their contributions.

    As salary negotiation practices continue to shift, candidates who adapt will be better positioned to advocate for themselves. Understanding the implications of refusing to disclose salary history is crucial for effective negotiation strategies. Ultimately, the conversation surrounding salary disclosure is evolving. Candidates who embrace this change and stay informed about their rights will have a competitive edge in the job market. The focus on transparency and fairness in salary negotiations is likely to reshape hiring practices, benefiting both candidates and employers.

    The job interview question you don't have to answer

    Employers must conduct fair and equitable interviews. While they can ask about salary history, they must ensure their questions do not lead to discrimination. The Equality Act 2010 protects applicants from discrimination based on age, gender, and race. Employers are encouraged to standardize interview questions to treat all candidates fairly. By asking each applicant the same questions, they can minimize biases and create a more inclusive hiring process. This practice benefits candidates and enhances the overall quality of hires.

    Furthermore, organizations should adopt transparent salary practices in job postings. By clearly stating salary ranges, they can attract candidates aligned with their compensation expectations. This reduces the chances of salary-related disputes during negotiations. Career Ahead’s analysis highlights that employers prioritizing transparency and fairness in hiring processes are more likely to attract top talent. As candidates become more informed about their rights, they will seek employers who respect those rights and foster a positive workplace culture.

    In the evolving job market, salary disclosure and negotiation practices will shape hiring trends. Employers who adapt to these changes will enhance their reputation and contribute to a more equitable workforce. As discussions around salary practices grow, both candidates and employers must navigate this landscape carefully. The future of salary negotiations depends on a mutual understanding of rights and responsibilities. Job seekers in the UK can now advocate for themselves more effectively. As the conversation around salary disclosure evolves, it will be interesting to see how both candidates and employers adapt to these job market changes.

    Frequently Asked Questions

    Can I refuse to answer salary questions during an interview?

    Yes, you can refuse to disclose your salary history during an interview. Employers may ask, but you are not obligated to answer if you feel uncomfortable.

    What should HR professionals know about salary disclosure laws?

    HR professionals should know that while asking about salary history is allowed in the UK, candidates have the right to refuse to answer. They should also consider standardizing questions to ensure fairness in hiring.

    The job interview question you don't have to answer

    How can job applicants prepare for salary discussions in interviews?

    Job applicants can prepare by researching market rates for their roles and clearly articulating their skills and contributions. This preparation allows them to negotiate confidently and effectively.

  • Secure Your Investments for Family After Your Passing

    Secure Your Investments for Family After Your Passing

    India — Investors with diverse portfolios, including mutual funds, stocks, and fixed deposits, have a major concern. They want to ensure their families can access these assets after their death. A recent report highlights the need for an organized inventory of investments. As financial products become more complex and scattered, clarity and accessibility are crucial.

    Experts advise investors to create a detailed asset inventory. This inventory should include all financial holdings, types of investments, account numbers, and associated institutions. By doing this, families can easily locate and claim these assets during a time of grief. This helps avoid unnecessary complications. A report by Mint states that tracing investments is difficult when they are spread across multiple banks, mutual funds, demat accounts, and insurance policies. Thus, a consolidated asset inventory is essential for effective estate management.

    Importance of Estate Planning for Investors

    Estate planning is vital for anyone with investments, no matter their size. It ensures your financial legacy passes smoothly to your heirs. Experts say that simply naming a nominee is not enough. A nominee acts as a custodian, but a legally binding will detailing the beneficiaries is crucial. This helps avoid disputes and ensures your wishes are honored. Career Ahead’s analysis shows many investors overlook the need for a will. A will specifies who gets what and simplifies the process for your family. If an investor has multiple assets across different platforms, a will guides heirs through the complexities of asset transfer.

    Moreover, keeping the will updated is as important as creating it. Changes in family dynamics, like marriages, births, or deaths, may require updates to the will. Investors should regularly review their estate plans to reflect their current wishes. The report from Mint highlights that failing to maintain an updated will can lead to serious complications. Legal disputes among heirs can be emotionally and financially draining.

    In addition to a will, experts recommend keeping a list of all financial assets. This list should include account numbers, contact information for financial institutions, and relevant passwords. Such transparency can significantly ease the burden on family members during a tough time. Minisha Rupani, Senior Vice President at Anand Rathi Wealth, stresses that a consolidated asset inventory is crucial. This inventory should cover all types of investments, including mutual funds, stocks, and fixed deposits, along with their account details. An organized approach can prevent assets from becoming unclaimed due to lack of information, a common issue for families dealing with a deceased relative’s estate.

    Tools for Documenting Investments

    Several tools and methods can help investors document their financial assets effectively. One recommended approach is to create a digital or physical file with all investment-related documents. This file should be easily accessible to trusted family members. For example, an Excel spreadsheet can track various investments, providing a clear overview of what is owned and where it is held. This method aids organization and ensures family members can quickly find necessary information.

    Besides an asset inventory, investors should track their financial accounts’ log-in details. This includes usernames and passwords for online accounts. While it may seem trivial, this information is vital for heirs to access and manage investment accounts. A secure password manager can help keep this information organized and safe. Additionally, using platforms that offer consolidated views of investments can simplify the process. Many financial apps allow users to link multiple accounts, providing a comprehensive overview of their financial landscape. This is especially beneficial for those with investments across different banks and financial institutions.

    Career Ahead research shows that a lack of structured asset documentation can lead to significant challenges for families. For instance, unclaimed assets may eventually go to the Investor Education and Protection Fund (IEPF) if not claimed within a certain timeframe. This highlights the importance of proactive management of financial records. Investors should also communicate openly with their families about their financial situation. Regular discussions can clarify the investment landscape and prepare heirs for what to expect. This transparency aids asset management and fosters a sense of responsibility among family members.

    Secure Your Investments for Family After Your Passing

    Effective communication is key to preparing heirs for managing financial assets. Investors should hold family meetings to discuss their financial situation and the importance of managing investments. This can educate younger family members, equipping them with the knowledge to handle financial matters responsibly. In these discussions, it’s essential to cover the basics of investments, including how to access accounts, the importance of diversification, and the implications of financial decisions. By instilling financial literacy in heirs, investors can help ensure their legacy is preserved and managed wisely.

    Additionally, providing heirs with a written summary of financial assets, including the location of important documents and instructions for accessing accounts, can be invaluable. This summary should be clear and concise, making it easy for family members to follow during a challenging time. Experts also suggest involving a trusted family member or advisor in these discussions. This person can act as a point of contact for heirs, guiding them through the estate management process and ensuring all necessary steps are taken.

    Finally, as situations change, such as the passing of the investor or changes in family dynamics, it is crucial to revisit these discussions regularly. Keeping communication open ensures that all family members remain informed and prepared. As the financial landscape evolves, the importance of proper asset management and communication cannot be overstated. Investors must take proactive steps to ensure their financial legacy is preserved and accessible to their loved ones.

    What will happen if families do not take these steps? The risk of unclaimed assets and disputes over inheritance is significant. This makes it imperative for investors to act now. The future of family wealth management may depend on the actions taken today.

    Frequently Asked Questions

    How can I organize my investments for my family?

    Creating a consolidated asset inventory is key. This should include all financial accounts, investment details, and nominee information. Keeping this document updated and accessible will help your family locate your investments after your death.

    What documents should I prepare for my heirs regarding my investments?

    Prepare a will that specifies beneficiaries and maintain a list of all financial assets, including account numbers and contact information for institutions. This information will streamline the process for your heirs.

    Secure Your Investments for Family After Your Passing

    What steps should investors take to ensure their family can access their financial assets?

    Investors should create a comprehensive asset inventory, keep their will updated, and communicate openly with their family about their financial situation. This proactive approach can greatly ease the burden on heirs during a difficult time.

  • Young Professionals Secure Jobs Through LinkedIn Networking

    Young Professionals Secure Jobs Through LinkedIn Networking

    New York, US — Young professionals are increasingly turning to LinkedIn to secure job offers, with many sharing success stories of sending hundreds of personalized messages. A recent report highlights how one individual sent over 200 LinkedIn messages, leading to a job offer. This approach underscores the importance of proactive networking in today’s competitive job market.

    Networking has evolved significantly, especially for recent graduates and entry-level job seekers in tech and marketing. As the job market becomes more saturated, the ability to connect with potential employers and industry professionals through platforms like LinkedIn is more critical than ever. Nicole Leverich, LinkedIn’s Chief Communications Officer, emphasizes that building a network can happen in various ways, including online interactions, casual conversations, or formal networking events.

    The Power of Personalized Outreach

    Career Ahead’s analysis finds that personalized outreach on LinkedIn significantly increases engagement rates. A study shows that only 17% of LinkedIn connection requests include a personalized message, yet these requests receive 300% higher acceptance rates than generic invitations. This highlights the effectiveness of tailoring messages to the recipient, making them feel valued and recognized.

    When reaching out to potential connections, it is crucial to reference something specific about their profile or recent activity. For instance, mentioning a common interest or commenting on a post can create a connection that feels more genuine. Leverich advises that it is essential to keep requests clear and specific, allowing recipients to respond without feeling overwhelmed.

    Furthermore, Leverich suggests that networking should not feel transactional. Instead, young professionals should aim to build relationships before they need something. Engaging with others by asking for advice or insights can foster a more meaningful connection, ultimately leading to job opportunities. This approach aligns with findings from simplestic.com, which emphasizes the importance of nurturing professional relationships over time.

    In practice, this means identifying individuals in desired industries and starting conversations well before a job search begins. By establishing rapport with professionals in advance, job seekers can position themselves as valuable candidates when opportunities arise.

    Crafting Effective LinkedIn Messages

    Crafting effective LinkedIn messages is an art that can significantly impact a job seeker’s success. Career Ahead research identifies several key strategies for writing messages that resonate with recipients. First, it is essential to keep the message concise and focused. A well-structured message should clearly state the purpose of the outreach and what the sender hopes to achieve.

    Incorporating elements of gratitude is another effective strategy. Acknowledging the recipient’s time and expertise can create a positive impression and encourage them to respond. Leverich notes that a simple ‘thank you’ can go a long way in fostering goodwill and encouraging further interaction.

    Additionally, young professionals should be mindful of their tone and language. Messages should be professional yet approachable, reflecting the sender’s personality while maintaining a level of professionalism. This balance can help establish a connection that feels authentic and inviting.

    Young Professionals Secure Jobs Through LinkedIn Networking

    Another crucial aspect is to follow up on initial messages. If a recipient does not respond, sending a polite follow-up can demonstrate persistence and genuine interest. However, it’s essential to strike a balance and avoid being overly aggressive or pushy, as this can deter potential connections.

    Leverich’s advice to engage with content on LinkedIn before reaching out can also be beneficial. By liking, commenting, or sharing posts, young professionals can increase their visibility and make their names familiar to potential connections, setting the stage for a more effective outreach.

    Networking’s Role in Job Acquisition

    The impact of networking on job acquisition cannot be overstated. Career Ahead’s analysis shows that nearly 44% of Generation Z professionals cite a lack of the right network as a significant barrier to landing entry-level roles. This statistic underscores the necessity of building a robust professional network early in one’s career.

    Networking is not just about quantity but quality. The depth of connections and the strength of relationships can lead to referrals, recommendations, and insider information about job openings. This is particularly important in industries where competition is fierce, and opportunities can be limited.

    Young professionals should also leverage their existing networks. Often, connections from school, internships, or previous jobs can provide valuable insights and introductions. Leverich emphasizes that everyone starts with a network, and it’s essential to tap into those connections to expand further.

    Young Professionals Secure Jobs Through LinkedIn Networking

    Moreover, engaging with mentors can significantly enhance a young professional’s career trajectory. Mentors can provide guidance, support, and introductions to key industry players, making them invaluable allies in the job search process. As noted by betterup.com, having a mentor can improve career outcomes and increase job satisfaction.

    As the job market continues to evolve, the ability to network effectively will remain a crucial skill for young professionals. The emphasis on building relationships and engaging authentically will likely shape how future job seekers approach their career paths.

    Frequently Asked Questions

    How many LinkedIn messages should I send to get a job?

    Career Ahead analysis shows that sending around 50-100 personalized LinkedIn messages can increase your chances of receiving positive responses. However, the focus should be on quality over quantity, ensuring each message is tailored and meaningful.

    What should recent graduates in marketing include in their LinkedIn messages?

    Recent graduates in marketing should include a brief introduction, mention any shared connections or interests, and clearly state their purpose for reaching out. Personalizing the message increases the likelihood of a response.

    Young Professionals Secure Jobs Through LinkedIn Networking

    How can entry-level job seekers in tech improve their networking skills?

    Entry-level job seekers in tech can improve their networking skills by engaging with industry content on LinkedIn, reaching out to professionals for informational interviews, and practicing their messaging strategies to build confidence and clarity.

  • Essential Financial Steps for Expats Moving Back to India

    Essential Financial Steps for Expats Moving Back to India

    India is witnessing a significant trend of expatriates returning home after years abroad, driven by evolving job markets and personal choices. As these individuals prepare for their return, understanding the financial landscape is crucial.

    Moving back to India involves more than just packing; it requires careful financial planning. Expats often have retirement accounts, foreign investments, and bank accounts that need proper management. The financial choices made before relocating can greatly affect their future in India.

    Tax Considerations for Returning Expats

    One critical aspect for returning expats is the tax implications of moving assets. According to the Income Tax Department, returning to India does not automatically change an individual’s tax residency status. Factors such as the number of days spent in India and past residency history are key in determining tax obligations.

    Individuals returning after several years may qualify as “Not Ordinarily Resident” (RNOR) for a limited time, which can influence how overseas income is taxed. Understanding the Double Taxation Avoidance Agreement (DTAA) is essential to avoid double taxation on foreign investments.

    Mandatory disclosures of foreign assets become crucial once residency is established in India. Failing to report overseas assets can lead to significant penalties. Therefore, it is wise for expats to familiarize themselves with Indian tax laws before making the move.

    Investment Opportunities in India

    Returning expats have a unique opportunity to invest in the growing Indian market. With the economy rebounding, there are numerous investment options that can yield good returns. Real estate is a popular choice for many expats looking to settle back in India.

    Investing in property can provide both a home and a potential income source through rentals. Understanding local real estate trends and regulations is essential, and working with local experts can facilitate effective navigation of the market.

    The Indian stock market also offers various investment options. Expats may want to diversify their portfolios by investing in mutual funds or Exchange Traded Funds (ETFs) that focus on Indian companies, allowing them to benefit from the growth potential of the Indian economy while managing risk.

    Additionally, fluctuations in currency value can significantly affect returns on investments made in foreign currencies. A phased approach to currency conversion can help mitigate risks associated with sudden changes in exchange rates.

    Currency Exchange and Banking Strategies

    Currency exchange is another important factor for returning expats. They often have savings in foreign currencies, which can lead to losses if exchanged too quickly. A strategic approach to currency conversion can help maximize the value of these funds.

    Expats should consider maintaining foreign currency accounts in India, as some banks allow NRIs to hold accounts that facilitate easier currency conversions. It is advisable to consult financial institutions about the best options available.

    Updating banking needs is crucial. Expats should transition from NRE or NRO accounts to resident accounts to ensure compliance with Indian regulations, which can also provide better interest rates and services.

    6 Financial Moves for Expats Returning to India

    Furthermore, understanding the implications of foreign investments is essential. Many expats overlook the need to report these assets in their Indian tax returns. Keeping track of foreign investments and ensuring compliance with Indian laws can prevent future complications.

    Healthcare and Insurance Considerations

    Healthcare should be among the first financial issues to examine, particularly if returning to India in later years. Expats should verify whether their overseas health insurance policy will continue to provide coverage in India and whether they need to purchase an Indian health insurance policy.

    When comparing policies in India, carefully examine waiting periods, co-payment requirements, exclusions, and the network of hospitals offering cashless treatment. The Insurance Regulatory and Development Authority of India (IRDAI) permits portability of eligible health insurance policies between Indian insurers at renewal, allowing credits for pre-existing diseases and specific waiting periods to be carried forward.

    6 Financial Moves for Expats Returning to India

    Risks, Trade-Offs, and What Comes Next

    As more expats return, understanding the financial landscape in India becomes increasingly important. With the right strategies, these individuals can effectively navigate their financial obligations and opportunities. Proactive planning in tax, investment, currency exchange, and healthcare can lead to a smoother transition back to India.

    Frequently Asked Questions

    What are the tax implications for expats returning to India?

    Returning expats must know that their tax residency status depends on various factors, including the number of days spent in India. Many may qualify as Not Ordinarily Resident (RNOR), impacting how their overseas income is taxed.

    How can I invest my savings effectively in India?

    Expats have many investment opportunities in India, including real estate and the stock market. Working with local financial advisors can help create investment strategies that align with personal financial goals.

    What should expats do about currency exchange before returning to India?

    Expats should consider a phased approach to currency conversion to reduce risks from exchange rate fluctuations. Consulting banks about maintaining foreign currency accounts can also be helpful.

  • Why a 780 Credit Score Doesn’t Guarantee Home Loan Approval

    Why a 780 Credit Score Doesn’t Guarantee Home Loan Approval

    India — A high credit score, such as 780, can significantly enhance a home loan application. However, it does not guarantee approval. Lenders consider a multitude of factors beyond credit scores when making lending decisions. Recent insights shed light on why even those with excellent credit can face rejection.

    Homebuyers often express surprise when their mortgage applications are denied, despite boasting a strong credit score. This situation underscores the complexities of lending, where lenders assess various criteria to evaluate a borrower’s financial health. Understanding these factors is crucial for high-credit-score homebuyers and the mortgage brokers who assist them.

    Understanding Lender Assessments

    A credit score of 780 indicates a solid repayment history, but it is merely one component of a lender’s assessment. According to a recent analysis by Mint, lenders also evaluate income stability, existing financial commitments, and the overall debt-to-income ratio. This comprehensive evaluation helps lenders determine if a borrower can manage the loan amount requested.

    For instance, if a borrower has high existing EMIs (Equated Monthly Installments) relative to their income, lenders may perceive them as a higher risk. The debt-to-income ratio is a critical metric that lenders analyze to assess repayment capacity. A high ratio may suggest that the borrower is over-leveraged, potentially leading to difficulties in meeting future financial obligations. Mint notes that lenders are increasingly cautious about borrowers who appear financially stretched, regardless of their credit score.

    The Role of Employment History

    Employment history plays a vital role in the approval process. Lenders prefer applicants with stable and consistent jobs, as this indicates reliable income. Frequent job changes or gaps in employment can raise concerns for lenders, prompting them to reconsider the application, even with a good credit score. According to Faster Capital, a solid employment history can enhance a borrower’s profile, while instability can create doubts about their ability to make consistent payments.

    Career Ahead analysis reveals that lenders focus more on the borrower’s overall financial profile, including job stability and income consistency. For high-credit-score applicants, even minor discrepancies in income or employment can lead to rejection. Therefore, it is essential for borrowers to present a well-rounded financial picture when applying for a home loan. Lenders often require additional documentation to verify claims, complicating the approval process.

    Importance of Documentation and Property Value

    In addition to financial metrics, the quality and completeness of documentation can significantly impact approval chances. Lenders require thorough documentation to verify income, employment, and the property being financed. Incomplete or inaccurate documentation can result in delays or denials, even for applicants with high credit scores. Mint highlights that many applicants underestimate the importance of providing complete documentation, which may include tax returns, pay stubs, and proof of other income sources.

    Why a 780 Credit Score Doesn’t Guarantee Home Loan Approval

    Moreover, the nature and value of the property are critical in the approval process. Lenders will assess whether the property meets their lending criteria and if its value justifies the loan amount. If the property has issues, such as being in a less desirable location or needing significant repairs, lenders may hesitate to approve the loan, regardless of the borrower’s credit score. The BBC notes that lenders are particularly cautious in fluctuating real estate markets, where property values can change rapidly. It is essential for borrowers to ensure their chosen property is a sound investment.

    Preparing for Loan Applications

    Given the multifaceted nature of loan assessments, homebuyers must recognize that a strong credit score is just the starting point. They should also focus on managing debt levels and maintaining stable employment to improve their loan eligibility. Mortgage brokers play a crucial role in educating clients about the factors affecting loan approval. By helping clients understand the importance of their overall financial profile, brokers can better prepare them for the lending process.

    This preparation may include advising clients on improving their debt-to-income ratios or ensuring they have all necessary documentation ready before applying. As the lending landscape evolves, homebuyers with high credit scores should remain vigilant. The key takeaway is that while a high credit score is advantageous, it does not guarantee loan approval. Instead, it is one of many factors that lenders consider, highlighting the need for a comprehensive approach to financial health.

    Why a 780 Credit Score Doesn’t Guarantee Home Loan Approval

    Frequently Asked Questions

    What factors can lead to mortgage rejection despite a high credit score?

    High existing debt levels, inconsistent employment history, and incomplete documentation can lead to mortgage rejection, even with a high credit score. Lenders evaluate the overall financial profile, not just the credit score.

    How can mortgage brokers better prepare clients for loan applications?

    Mortgage brokers can prepare clients by educating them on the importance of a complete financial profile, including debt-to-income ratios and employment stability. Ensuring clients have all necessary documentation ready can also improve their chances of approval.

    What should homebuyers do if their loan application is rejected?

    If a loan application is rejected, homebuyers should review their financial profile and address any weaknesses, such as high debt levels or incomplete documentation. Consulting with a mortgage broker can provide valuable insights into improving future applications.

  • Recognize Bad Debt Before It Drains Your Finances

    Recognize Bad Debt Before It Drains Your Finances

    Rising interest rates are putting financial pressure on young professionals worldwide. Many recent graduates, burdened by student loans, face a critical point where their debt could shift from manageable to unmanageable, affecting their financial health and career prospects.

    As of September 2026, the financial landscape has changed dramatically. Interest rates have surged, and many graduates feel the strain of their loans. This situation calls for a closer look at good versus bad debt. According to a report by Mint, good debt can help with education, home ownership, or business growth, while bad debt incurs high costs without lasting benefits.

    Identifying Bad Debt Indicators

    Career Ahead’s analysis identifies several warning signs that student loans may be turning into bad debt. First, missed payments can signal a troubling trend. When borrowers miss payment deadlines, they face increased interest rates and extra fees, worsening their financial situation. A study by National Debt Relief emphasizes that missing payments can lead to long-term damage to credit scores, making future borrowing harder.

    Second, exhausted savings can indicate that borrowers rely too much on credit for basic needs, trapping them in a cycle of debt. According to the same National Debt Relief report, individuals who frequently borrow for everyday expenses are at high risk of accumulating bad debt. Rising living costs, which have outpaced wage growth, make it harder for young professionals to maintain financial stability.

    Third, repeatedly borrowing to pay off existing loans is another red flag. This practice often leads to a debt spiral, where the total amount owed increases without real progress toward repayment. As highlighted by Cents and Purpose, many ignore these signs until it’s too late, leading to severe financial distress. The stress of unmanageable debt can also harm mental health and overall well-being.

    Finally, young professionals should be cautious of high-interest loans, especially those linked to credit cards. The Reserve Bank of India warns that minimum payments on such debts can extend repayment periods and raise overall costs, making it harder for borrowers to regain control of their finances. The compounding nature of high-interest debt can lead to borrowers paying significantly more over time than they initially borrowed, creating a sense of hopelessness.

    Effective Debt Management Techniques

    Managing debt effectively is crucial for young professionals in these challenging times. One effective strategy is to create a detailed budget that outlines all income and expenses. This helps borrowers identify where to cut costs and allocate more funds toward high-interest debts. Additionally, contacting lenders before missing payments can provide options for restructuring loans. Many lenders are willing to work with borrowers facing financial difficulties, offering lower interest rates or extended repayment plans. Career Ahead’s research shows that proactive communication can significantly reduce financial stress.

    Moreover, maintaining an emergency fund is essential. Having savings for unexpected expenses can prevent reliance on credit cards or loans, which can lead to bad debt. Financial experts recommend that young professionals save at least three to six months’ worth of living expenses. This buffer can be vital during economic uncertainty, allowing borrowers to handle unexpected challenges without resorting to high-interest borrowing.

    Lastly, regularly reviewing loans and financial commitments is vital. Tracking changes in income or expenses can help borrowers adjust their repayment strategies. Career Ahead’s analysis emphasizes the importance of staying informed about one’s financial situation to avoid bad debt. By being proactive and regularly assessing their financial health, young professionals can make informed decisions that will benefit their long-term financial stability.

    Debt Warning Signs: Avoid Costly Mistakes

    Credit scores play a significant role in determining financial health, especially for young professionals. A low credit score can limit access to favorable loan terms, making it harder to refinance existing debt or secure new loans. Career Ahead’s findings indicate that many recent graduates underestimate the importance of maintaining a good credit score. Rising interest rates can worsen this issue. As lenders tighten their requirements, individuals with lower credit scores may face higher interest rates, complicating their financial situation. This cycle can have a long-term impact on their financial health, making it crucial for young professionals to prioritize credit score management.

    Young professionals should regularly check their credit reports for inaccuracies and take steps to improve their scores. Paying bills on time, reducing credit card balances, and avoiding new debt can help enhance credit scores over time. According to National Debt Relief, even small improvements in credit scores can lead to better loan terms and lower interest rates. As the financial landscape continues to evolve, young professionals must stay vigilant about their debt management strategies. The relationship between student loans, interest rates, and credit scores will shape their financial futures.

    Frequently Asked Questions

    What are the signs that my student loans are becoming bad debt?

    Key indicators include missed payments, exhausted savings, and repeated borrowing to pay off existing loans. If you’re relying on credit to meet basic needs, it’s crucial to reassess your financial situation.

    How can young professionals manage their debt effectively?

    Creating a detailed budget, communicating with lenders, and maintaining an emergency fund are effective strategies. Regularly reviewing your loans and financial commitments can also help you stay on track.

    Debt Warning Signs: Avoid Costly Mistakes

    What should recent graduates do about rising interest rates affecting their loans?

    With rising interest rates, it’s important to stay informed about your financial situation. Consider refinancing options and prioritize paying off high-interest debts to mitigate the impact of increasing rates.

  • Tax Savings Strategies Beyond 80C

    Tax Savings Strategies Beyond 80C

    India’s salaried individuals are changing how they plan their taxes. As of September 2026, nearly 73% of taxpayers have chosen the New Tax Regime. This shift moves away from traditional methods that relied heavily on Section 80C investments. It marks a key moment for high-income earners looking for smarter tax-saving strategies.

    The New Tax Regime means tax planning is no longer just about last-minute investments for Section 80C benefits. Now, it is crucial to understand various exemptions, capital gains rules, and strategies like tax harvesting. These changes affect how financial advisors help clients maximize their tax savings.

    Understanding Capital Gains and Tax Harvesting

    Capital gains tax is vital for high-income earners. The timing of selling an asset can greatly impact the tax owed. For example, selling equity within 12 months leads to short-term capital gains taxed at 20%. In contrast, selling after 12 months qualifies for long-term treatment at a lower rate of 12.5%. This difference can result in significant tax savings, making timing crucial for investors.

    Tax harvesting is another effective strategy to manage capital gains tax. This involves selling securities at a loss to offset gains from profitable investments. Many individuals are unaware of this strategy or find it complex, especially DIY investors. However, understanding tax harvesting can greatly reduce overall tax liability. Additionally, the ability to carry forward losses to future tax years adds flexibility, helping investors optimize their tax positions over time.

    High-income earners can also benefit from a tax exemption on long-term capital gains of up to ₹1.25 lakh from selling listed equity assets. If an individual holds stocks or mutual fund units for more than 12 months, gains up to this amount will not be taxed. Reinvesting immediately after selling can reset the cost base, further enhancing future gains and tax efficiency. As noted by the Hindustan Times, many investors miss these details, leading to lost tax-saving opportunities.

    Tax awareness is low among retail investors. Financial advisors play a key role in educating clients about these strategies. Many clients may not realize they can save significant amounts on taxes by using tax harvesting or better understanding capital gains rules. This knowledge gap offers advisors a chance to improve their services, ensuring clients are informed and can make strategic decisions aligned with their financial goals.

    Capital Gains from Property Sales

    High-income earners can also optimize tax savings through property sales. Under Section 54 of the Income Tax Act, taxpayers can save on capital gains from selling a residential property if they reinvest the profits into another residential property or specified bonds. However, specific conditions must be met to keep the exemption.

    The property sold must have been held for at least 24 months to qualify for long-term capital gains treatment. Additionally, the proceeds must be reinvested within a set timeframe—either one year before or two years after the sale. If these conditions are not met, the exemption can be reversed, leading to higher tax liability. Financial advisors should make sure their clients understand these details to avoid unexpected tax bills. Many clients may overlook the timing and conditions related to property sales, missing tax-saving opportunities.

    There is also a cap on the maximum tax exemption available, set at ₹10 crore for reinvestment in a house property. For specified bonds under Section 54EC, the limit is ₹50 lakh per year. Knowing these limits and conditions is essential for investors looking to maximize tax efficiency when selling property. As more individuals invest in real estate, the complexity of capital gains tax calculations increases, especially for those with overseas investments. For example, the holding period for long-term treatment of foreign shares is 24 months, not 12, which can confuse many investors. Advisors must help clients navigate these complexities to ensure informed decisions.

    Tax Savings Strategies Beyond 80C

    Moreover, the implications of property sales go beyond immediate tax savings. Investors should consider the potential for property value appreciation over time, which can impact their overall financial strategy. As noted by Chattanoogatrend, understanding market trends and property valuation can help investors make better decisions about when to sell and reinvest, ultimately improving their financial outcomes.

    Advance tax is another important factor for high-income earners, especially those with extra income from rent, interest, or capital gains. Salaried professionals and freelancers must pay advance tax if their total tax liability exceeds ₹10,000 in a financial year. Not complying can lead to penalties ranging from ₹40,000 to ₹3.6 lakh.

    Career Ahead’s research shows that many individuals struggle to understand the details needed to file taxes accurately, leading to potential penalties. This highlights the need for solid financial planning and real-time tax liability calculations to avoid unexpected charges. Financial models that pull data from account aggregators can help calculate tax liabilities accurately and inform clients about their obligations.

    As tax regulations become more complex, the demand for comprehensive tax planning services from financial advisors grows. Clients unaware of their advance tax obligations risk facing significant penalties, affecting their financial health. Furthermore, as the tax landscape evolves, high-income earners must stay informed about changes that could impact their tax planning strategies. Keeping up with new regulations and exemptions will help them adapt their financial strategies accordingly.

    The shift from traditional tax-saving methods to innovative strategies marks a crucial moment for high-income salaried individuals. As they navigate this new landscape, understanding capital gains, tax harvesting, and advance tax will be key to optimizing their tax efficiency.

    It remains to be seen how these changes will affect the financial planning industry. Advisors must strive to keep their clients informed and compliant in this evolving tax environment.

    Frequently Asked Questions

    What are the best tax-saving options for high-income salaried individuals?

    High-income salaried individuals can explore various tax-saving options beyond Section 80C. These include capital gains strategies, tax harvesting, and reinvestment in property. Understanding these options can greatly enhance tax efficiency.

    How can financial advisors help clients maximize tax savings?

    Financial advisors can educate clients on innovative tax strategies, such as capital gains management and tax harvesting. By offering personalized guidance, advisors can help clients navigate complex tax regulations and optimize their financial planning.

    Tax Savings Strategies Beyond 80C

    What should financial advisors do about the new tax-saving strategies introduced in 2026?

    Financial advisors should stay updated on the latest tax regulations and educate their clients about innovative strategies. Understanding the New Tax Regime’s implications will enable advisors to provide informed recommendations to their clients.